How to make sense of ISO tax treatment (+ examples)
19 min
0 result
John’s a Director at Secfi, helping founders, executives and employees navigate equity compensation and access to liquidity through his expertise in finance.
Incentive stock options (ISOs) aren’t taxed when you’re granted them or when they vest.
When you exercise, you don’t owe regular income tax, but the spread between your strike price and the share’s fair market value counts toward the alternative minimum tax (AMT).
When you sell, the outcome depends on timing. If you hold the shares for at least one year after exercise and two years after grant, your whole gain is taxed at long-term capital gains rates. If you sell earlier, the spread at exercise is taxed as ordinary income.
That’s the framework. The amount you actually owe depends on your income, where you live, how many options you exercise and when, and this guide covers all of those, with a worked example.
Here, we cover:
Note. ISO taxation is a rabbit hole of complexity. While we've tried our best to provide a clear overview, how much tax you actually owe will depend on your specific circumstances.
That's why, if you want a reliable breakdown for your personal situation, you'll need something better than a general guide. Our AI equity assistant, Maeve, can help give you clarity on your potential tax liability and help you work out the best equity strategy for your position. It's free to use. As always, Mauve is for informational purposes only. Please always consult a tax professional regarding your particular situation.
| Event | Regular income tax | AMT | What you should know |
|---|---|---|---|
Grant | None | None | Nothing to report |
Vesting | None | None | Vesting only means you're now allowed to exercise |
Exercise | None | The spread (fair market value minus strike price) counts toward AMT | You may owe AMT for that tax year, even though you haven't sold anything |
Sale after holding 1+ year from exercise and 2+ years from grant (qualifying disposition) | Long-term capital gains on sale price minus strike price | AMT you paid earlier may come back as an AMT credit | The lowest-tax outcome |
Sale before those holding periods end (disqualifying disposition) | Ordinary income on the spread at exercise, then capital gains on any further growth | The AMT adjustment generally reverses if you sell in the same year you exercised | Taxed much like a non-qualified stock option (NSO) |
Incentive stock options are stock options that get more favorable tax treatment than non-qualified stock options (NSOs). Only employees can receive ISOs, which is why most startups use them for staff equity and use NSOs for advisors, contractors and board members.
Your options are granted on day one, but you usually can't exercise them all straight away. They follow a vesting schedule, which controls when you're allowed to exercise. A common setup is four years with a one-year cliff: 25% vests after your first year, and the rest vests monthly after that.
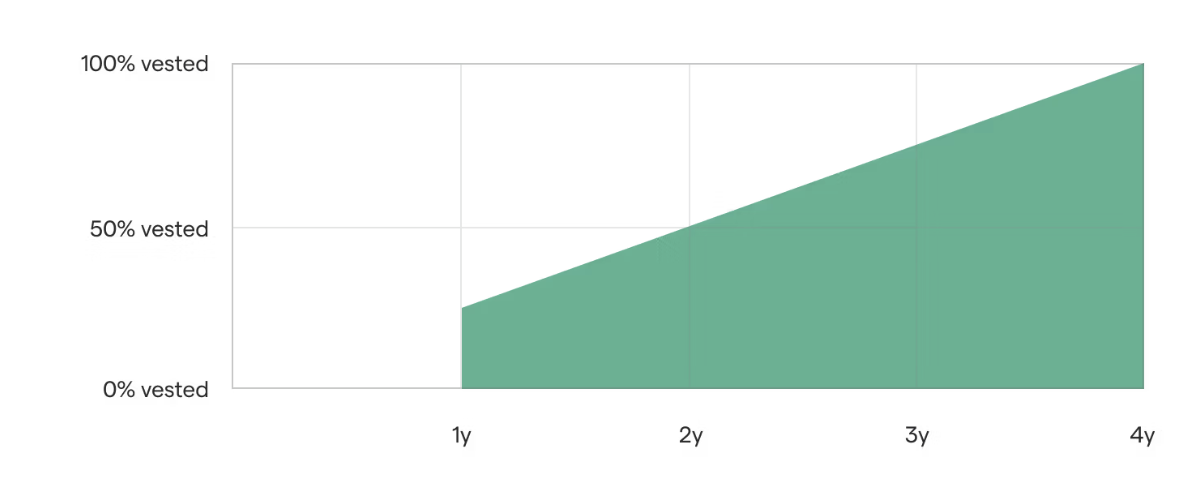
For illustrative purposes only. Actual results may vary, and there is no guarantee of any particular outcome.
Three rules shape everything that follows:
When you exercise an ISO, you pay the strike price and receive a share. You don't owe regular income tax on that exercise, which is the main advantage ISOs have over NSOs.
The catch is the alternative minimum tax (AMT). AMT is a separate tax calculation that runs alongside the regular income tax, designed to stop higher earners using deductions and tax breaks to pay too little. Each year you work out your tax under the regular rules and again under the AMT rules, then pay whichever is higher.
When you exercise ISOs, the difference between the strike price and the share's fair market value (usually the 409A valuation at a private company) is added to your income for AMT purposes. This is often called the "spread" or "phantom gain". You haven't made any money, but the IRS treats the spread as income for AMT.
Example: Your ISOs have a $3 strike price and the current 409A valuation is $35. Each option you exercise adds $32 of AMT income. Exercise 10,000 options and you've added $320,000 to your AMT income for the year.
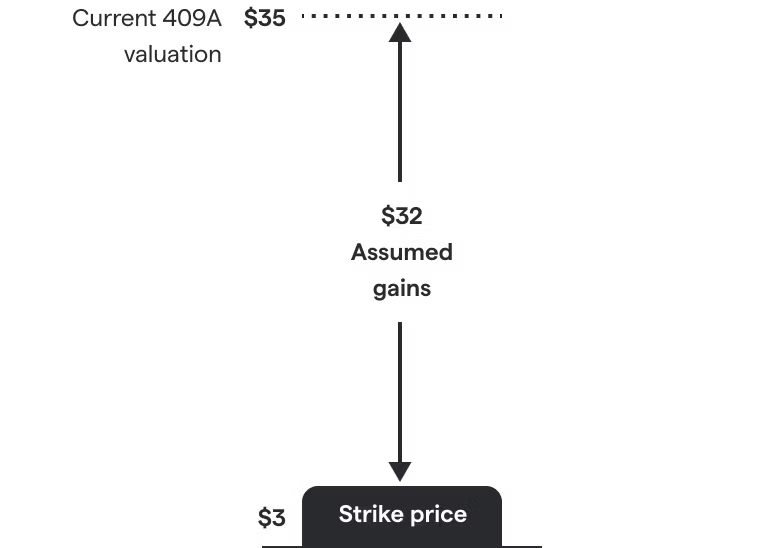
For illustrative purposes only. Actual results may vary, and there is no guarantee of any particular outcome.
Read a full guide on how stock options are taxed here: How are stock options taxed? What employees need to know before exercising
Everyone gets an AMT exemption, so you only owe AMT if your AMT income (including the spread) is high enough that the AMT calculation comes out higher than your regular tax. For 2026, the figures are:
| 2026 AMT figure | Single | Married filing jointly |
|---|---|---|
Exemption | $90,100 | $140,200 |
Exemption starts phasing out at | $500,000 | $1,000,000 |
Phaseout rate | 50 cents per dollar above the threshold | 50 cents per dollar above the threshold |
26% rate applies up to | $244,500 of AMT income (after exemption) | $244,500 |
28% rate applies above | $244,500 | $244,500 |
Some states have their own AMT, including California at 7%. A California employee with a large spread can face a combined federal and state AMT rate of up to roughly 35% on the portion that pushes them into AMT.
Using the example above, $11.20 of AMT per option ($32 × 35%) is a reasonable upper-end estimate for a California resident who's well into AMT territory. This is a simplified calculation: the actual AMT calculation is much more involved, and your number could be much lower, or zero, depending on your income and how many options you exercise.
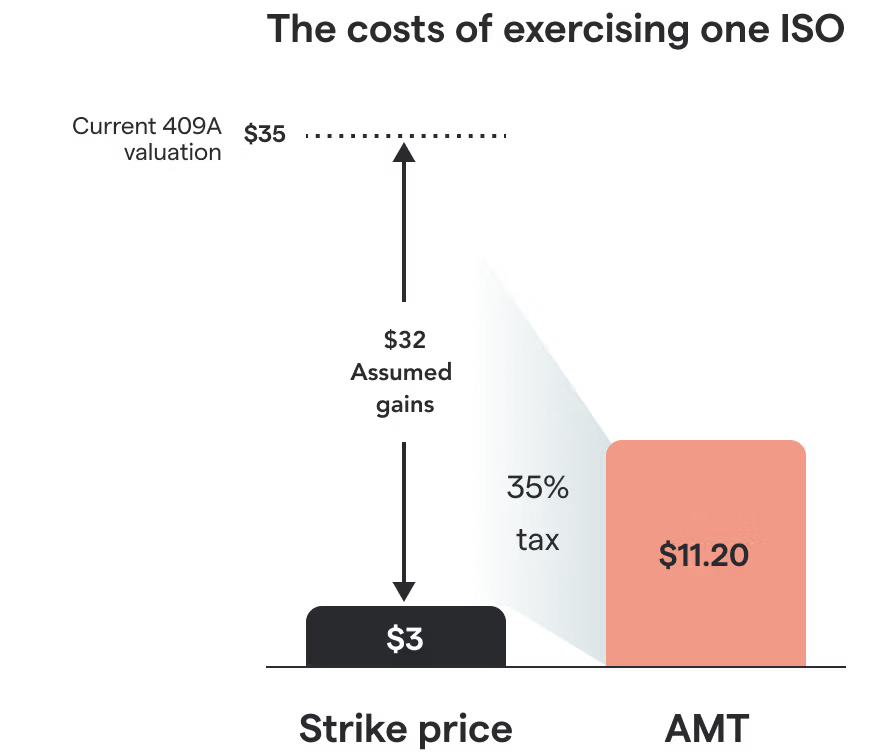
For illustrative purposes only. Actual results may vary, and there is no guarantee of any particular outcome.
Two practical points that can catch people out:
Because the spread usually grows as your company's 409A valuation rises, the same exercise generally costs more in AMT the longer you wait. Our AMT calculator estimates your threshold, and our guide on how to help avoid AMT when exercising ISOs covers strategies such as exercising in stages across tax years.
How your sale is taxed depends on whether it's a qualifying or disqualifying disposition.
If you sell at least one year after exercise and at least two years after the grant date, the sale is a qualifying disposition. Your whole gain (sale price minus strike price) is taxed at long-term capital gains rates of 0%, 15% or 20% at the federal level, depending on your income. High earners may also owe the 3.8% net investment income tax.
If you sell before either holding period ends, it's a disqualifying disposition.
The spread at exercise (fair market value at exercise minus strike price) is taxed as ordinary income, at the same rates as your salary. Any growth after exercise is taxed as a capital gain, short-term or long-term depending on how long you held the shares. If the sale price is lower than the fair market value at exercise, the ordinary income is generally limited to your actual gain.
Unlike NSOs, ordinary income from an ISO disqualifying disposition isn't subject to Social Security and Medicare taxes.
AMT and regular income tax are, in effect, two separate taxes. AMT you pay when you exercise ISOs creates an AMT credit (also called the minimum tax credit) for the amount you paid above what you would have owed under the regular rules.
You can use the credit to reduce your regular tax in later years, typically including the year you sell the shares, when the gain pushes your regular tax above your AMT. In a qualifying disposition, that's often enough to recover most or all of the AMT you paid upfront. Recovery isn't guaranteed, though. How much you can use each year depends on the gap between your regular tax and your AMT, so it can take several years, and some people never use all of it.
Typically, with stock options, you first exercise them to get a share and then you hope to later sell that share at a gain.
However, these two events can happen at the same time: you buy the share and immediately sell it, as if you had directly sold the ISO. You just have to wait until your company exits — otherwise its shares aren't sellable.
This is called a cashless exercise, since you don't have to come up with the cash to cover the upfront costs. It's a popular strategy because exercising prior to the exit can be expensive and risky. With a cashless exercise, you can immediately make money too, as the costs are withheld from your proceeds and you're guaranteed to have the cash to cover any taxes later on.
The trouble is, in terms of tax, a cashless exercise doesn't give you the long-term capital gains tax discount.
Instead, the two taxable events — exercising and selling — blend into one. In this case, you didn't exercise at least a year prior to selling, so you don't have a qualifying disposition. As such, your gains get taxed as ordinary income rather than as long-term capital gains.
Only $100,000 of ISOs can first become exercisable in any calendar year, measured at the share price on the grant date. Anything above that limit is treated as NSOs for tax purposes, which means ordinary income tax (plus Social Security and Medicare) on the spread at exercise.
This matters most if you received a large grant, received several grants with overlapping vesting, or have options that vest faster because of an acquisition. Our guide to the $100K rule and ISO/NSO splits explains how to work out which of your options count as which.
Say you join a startup and get 15,000 ISOs with a $3 exercise price. Eventually, the company IPOs and you get to sell the shares for $150 each.
Over time, the 409A valuation of your company grows on this timeline:
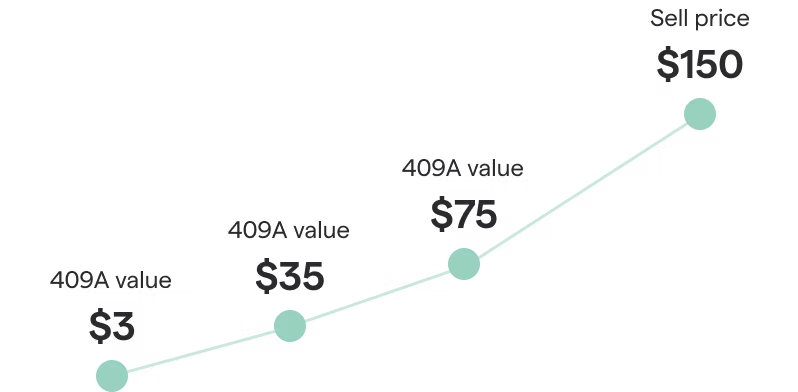
For illustrative purposes only. Actual results may vary, and there is no guarantee of any particular outcome.
Then this gives five distinct moments at which you could exercise:
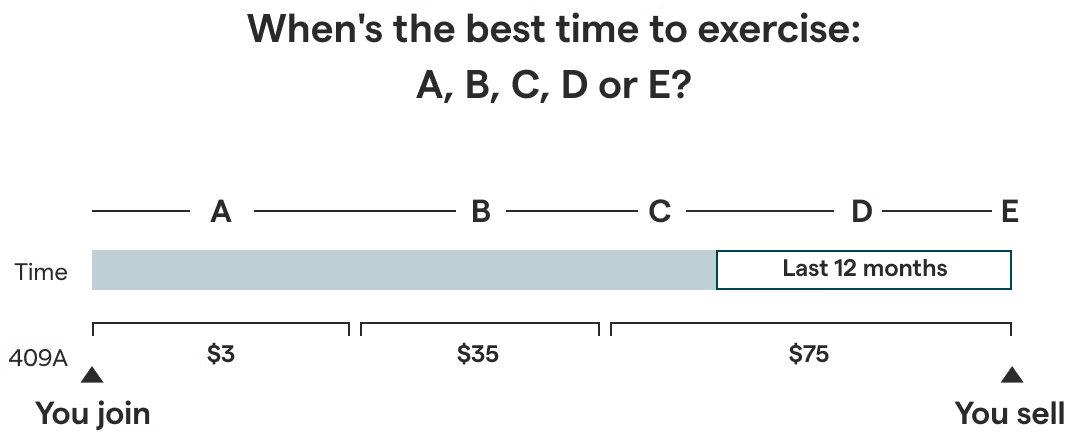
For illustrative purposes only. Actual results may vary, and there is no guarantee of any particular outcome.
You could exercise at any of these points in time. But, as you've seen above, the tax implications would be different at each. Plus, the amount of cash you need to exercise will change too.
Here's the amount of cash you'd need to exercise at A, B, C, D or E (remember, these numbers include the AMT you will owe upfront):
| Scenario | 409A at exercise | Spread per option | Strike cost | Total cash needed, including AMT |
|---|---|---|---|---|
A | $3 | $0 | $45,000 | $45,000 |
B | $35 | $32 | $45,000 | $261,000 |
C | $75 | $72 | $45,000 | $531,000 |
D | $75 | $72 | $45,000 | $531,000 |
E | n/a | n/a | Paid from proceeds | $0 |
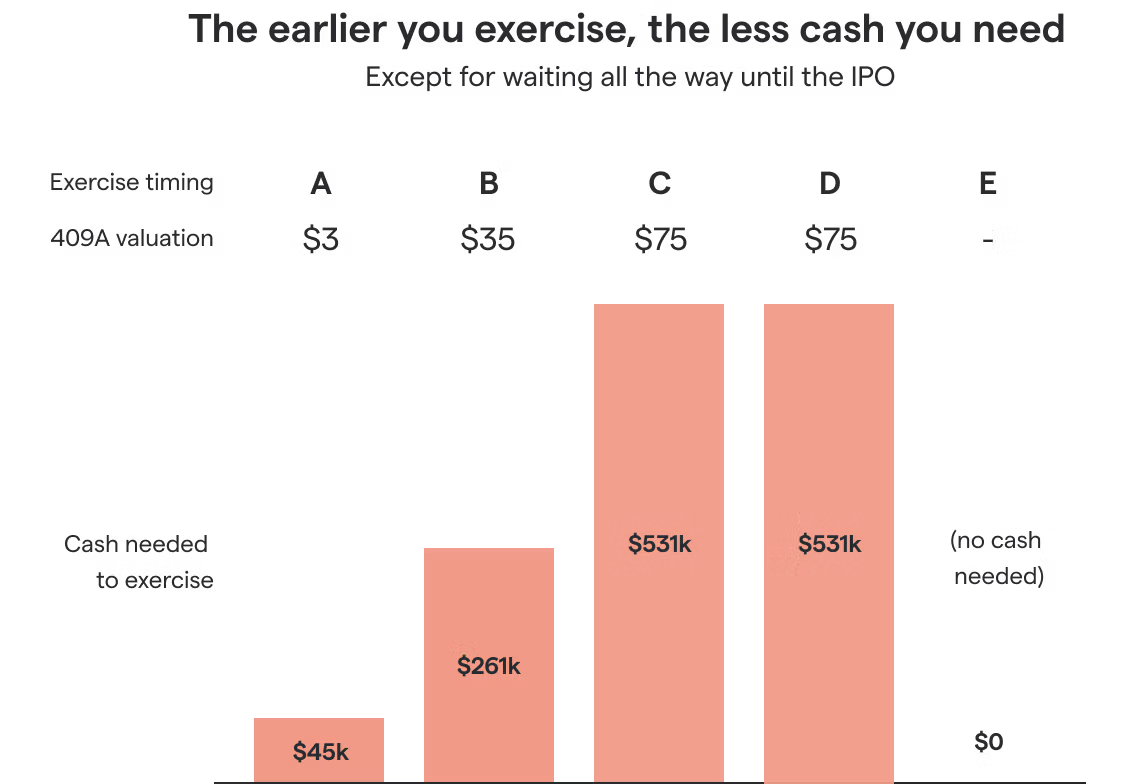
For illustrative purposes only. Actual results may vary, and there is no guarantee of any particular outcome.
If you wait all the way until you sell (point E), you don't need any cash to exercise, because you can cover the costs with your proceeds.
But if you exercise before selling, you need to pay out of pocket — and the higher the 409A, the more cash you need. If you do exercise before selling, though, you end up with a much higher net gain once the AMT credit comes back.
As you can see, if you exercise at least 12 months prior to selling — in this case at A, B and C — your net gain is higher:
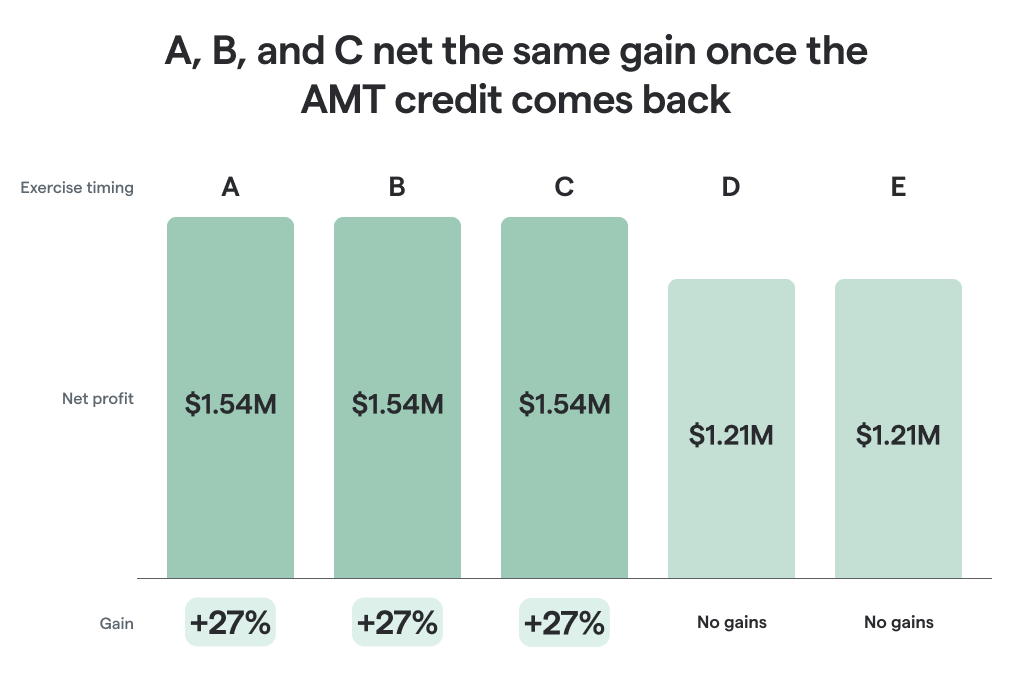
For illustrative purposes only. Actual results may vary, and there is no guarantee of any particular outcome.
The sums that you can owe in order to exercise can be quite intimidating. $261,000 or even $531,000 is a huge amount to pay upfront for your ISOs.
Unfortunately, these are pretty common numbers for employees at the most successful and high-growth startups. And even if you have that kind of money, putting your personal savings on the line is risky since it's not guaranteed that your company will actually manage to reach a successful exit.
So what do you do if you still want that tax savings? Or what if you recently left your company and now have a deadline to exercise?
That's exactly why exercise financing exists. Think of it as a way to access support to pay for your exercise, so you don't have to cover the costs upfront. Here's how it works:
In the rest of this guide, we share what we do at Secfi to help you get clarity on your equity position and finance your exercise.
Understanding the general rules around ISO taxation is only one part of the picture. Getting to grips with how it impacts you — and then making the right decision — is the real challenge.
At Secfi, we can help you navigate that challenge. We were founded to help startup employees navigate their equity compensation, and today we provide tools, guidance, and financing to make this as easy as possible.
So, whether you're trying to calculate your tax bill, evaluate the best time to exercise, or find the capital needed to purchase shares, Secfi can help you make decisions with confidence.
Here are three ways that we can help you maximize the value of your ISOs while managing your tax obligations.
ISO taxation can be complex because your tax bill depends on a range of factors, including how many shares you have, the strike price vs 409A valuation vs the sale price, and the timing of your exercise and sale.
That's why general advice is only of limited value when you're looking to understand how much you might owe. You really need guidance, with information specific to your particular circumstances.
Our AI equity assistant, Maeve, offers exactly that. Maeve uses data you provide to help you understand the tax implications of different exercise strategies before you make a decision. To make that easy, you can directly with Carta and other cap table software so you seamlessly import the relevant details of your equity.
You'll be able to clearly see your phantom gain and any potential AMT impact, the cash required to exercise, and any potential proceeds under different exit outcomes. Plus, you can model scenarios such as:
Unlike other AI tools, Maeve uses data on your specific equity and your financial position, to give you reliable, tailored forecasts. It's an easy way to get answers to equity and tax questions in plain English, based on your actual financial situation. Again, it's very important you review this information with a tax professional.
Every employee's financial situation is different, and ISO decisions should be considered within the context of your broader financial goals.
That's why it can be useful to talk to an expert equity strategist, to help you figure out and evaluate what actions you can take to maximize the value you get from your ISOs.
At Secfi, our equity strategists can help you to make decisions on when to exercise and sell — and give you clarity on key considerations, such as how much you'll need to pay in AMT liability. They'll talk you through the potential tax consequences of different options and help you to maximize your wealth long-term.
Plus, they'll help you develop a personalized plan that aligns your equity decisions with your broader financial objectives, so you can take a wider view of your wealth strategy. For instance, together you can consider your net worth and how much of it is tied up in company stock.
As we shared above, many employees understand the value of their ISOs but lack the cash needed to exercise them. At exercise, you need to cover not just the strike price, but any AMT obligations and other taxes transaction expenses.
At Secfi, we offer non-recourse financing specifically for startup equity holders. If you're eligible, we can help you to:
As our financing is non-recourse, your personal assets are protected if your company doesn't achieve a successful exit.
It's one way to exercise your options early with less personal risk, so you can more easily access the upside of share ownership.
For many startup employees, there are two key challenges when it comes to ISO exercise:
Victor, an engineering leader at a pre-IPO startup, faced exactly these problems.
First, he'd tried to work out his tax liabilities himself. He built a number of charts that would model different scenarios and how much AMT he'd owe. But he really wanted to be sure he was getting it right.
Victor's bigger problem was that he'd saved money to cover the cost of exercise, but he hadn't considered the AMT costs. Having run his numbers, he felt he could cover the tax bill, but it wouldn't be comfortable.
That's why Victor ultimately turned to Secfi.
Secfi helped him understand the potential tax implications of exercising, including how AMT could affect his situation, and provided financing to cover both the exercise cost and potential tax liability.
And because the financing was non-recourse, he could participate in his company's upside without risking his personal savings. He also highlighted the clarity and guidance he received throughout the process, helping him make a decision that fit his financial goals and risk tolerance.
Read the full case study here: Why this engineering leader chose Secfi to finance his stock options
Testimonials are specific to an individual Client's experience and may not be representative of all Clients. Unless otherwise indicated, Clients offering a Testimonial do not receive compensation and their statement does not present a conflict of interest.
Getting the most out of your ISOs requires careful planning. The timing of exercise, the impact of AMT, and whether you qualify for long-term capital gains treatment can all have a significant effect on your eventual returns.
As such, there's no one-size-fits-all strategy. That's why it's important to understand not just the general rules around ISO taxation, but how they apply to your specific circumstances.
Whether you're evaluating when to exercise, estimating your potential tax bill, or looking for a way to fund your exercise without tying up personal savings, Secfi can help.
We offer personalized guidance, scenario modeling, and non-recourse financing — to help you make informed equity decisions and maximize the value of their ownership.
Try our AI equity assistant, Maeve, for free, to start planning your equity strategy.
The tax impact of exercising ISOs depends on factors such as your strike price, your company's current 409A valuation, your income, your filing status, and where you live. In particular, you may owe AMT on the spread between your strike price and the fair market value of the shares.
Because every situation is different, it's often helpful to model multiple exercise scenarios before making a decision. Tools like Maeve, our AI equity assistant, can help you estimate potential tax liabilities and compare different exercise strategies.
Not necessarily. Exercising early can help reduce AMT exposure and start the clock on your holding period requirement, potentially lowering your future tax bill through long-term capital gains. However, exercising also requires cash upfront and involves risk, since there's no guarantee your company will have a successful exit.
The best approach depends on your financial situation, your confidence in the company, and your long-term goals.
Many startup employees find that the cost of exercising options and paying potential taxes is prohibitively expensive. In these situations, some choose to wait until a liquidity event, while others explore exercise financing.
Providers such as Secfi offer non-recourse financing that can cover exercise costs and taxes, allowing employees to exercise without putting their personal savings or assets at risk.
The tool shown here uses artificial intelligence and is for illustrative purposes only and not necessarily indicative of future results and there is no guarantee that similar results can be achieved. The information provided by the tool is not professional advice and is not intended by Secfi, Inc., its affiliates, and Secfi representatives, to be deemed as investment, legal, tax or other professional advice or recommendations of any kind, or to form the basis of any decision to do or to refrain from doing anything. Secfi does not review the accuracy or completeness of the information provided to us within the tool.