California equity and RSU tax: What happens if you move out of state?
19 min
0 result
Mike’s a CPF® at Secfi. He specializes in helping clients make the most of their stock options and integrate equity compensation into their broader financial plans.
If you're planning to move out of California and have unvested RSUs, you may still owe California tax after you leave. Moving to another state doesn't automatically end California's claim on compensation tied to work you performed while you lived or worked there.
Leaving California can reduce your tax burden, as its income tax is the highest rate in the country. But moving across state lines raises a few questions:
Can California still tax some of your future RSU income?
Does it matter whether your RSUs vest before or after you move?
Could you end up owing tax in both California and your new state?
The answer to all of those is: maybe. Taxes can be complicated, but in this guide we'll help sort it out. We'll explain:
How California taxes RSUs after you move out of state
How to define when you are no longer a California resident
When moving across state lines affects equity compensation
Restricted stock units (RSUs): Taxation when vesting and sale
Incentive stock options (ISOs): Taxed at exercise for AMT and at sale for capital gains
Non-qualified stock options (NSOs): Ordinary income tax at exercise and capital gains tax when sold
Employee Stock Purchase Plans (ESPP): Taxes When You Sell
What happens to RSUs if you move back to California?
How Secfi can help you plan your equity before or after a move
Not sure how moving out of California could affect your RSUs? Maeve, Secfi's free AI equity assistant, can help you understand your grant details and explore different vesting and tax scenarios.
Moving out of California doesn't necessarily mean California stops taxing your RSUs.
If your RSUs vest after you become a nonresident, California can still tax the portion of that income connected to work you performed in the state. The California Franchise Tax Board (FTB) generally treats RSU income as compensation for services and looks at where those services were performed between the grant date and vesting date.
A common way to calculate the California portion is:
California Allocation Ratio = California workdays from grant to vest ÷ total workdays from grant to vest
The Allocation Ratio is then applied to the income you recognize when the RSUs vest.
Let's use a basic example, keeping in mind you should consult with a qualified tax professional or financial advisor before making any decisions about your own situation.
Imagine you received an RSU grant while working in California and continued at the same company for the next few years. Between the grant date and vesting date, you worked 600 days in California and 400 days after moving to another state.
In this simplified example, 60% of the relevant workdays were in California. That means California could generally treat 60% of the income from those RSUs as California-source income when they vest, even though you no longer live there.
This is why the date you move isn't the only date to take into account. Your grant date, vesting date, work location, and the number of working days spent in California can all affect how much RSU income California can tax.
Simply leaving the state doesn't necessarily mean you are no longer a resident. And which state taxes you may owe will be determined by when your residency is established in a new state.
California residency is a facts-and-circumstances test, so there isn't one simple rule that automatically makes you a nonresident.
In 1985, the Corbett v. Franchise Tax Board determined that there are 29 different factors that the California Franchise Tax Board will use when determining whether or not you are a California resident. Some of the factors include:
Mailing address
Number of days present in the state
Voter registration
Car registration
Driver's license
Where you own real estate and/or rent property
Where your spouse and/or children reside
Basically, just because you cross state lines doesn't mean you're no longer a resident of that state. If, for example, you leave California and stay with family while you look for a house to buy, or an apartment to rent, you could still be considered a California resident during that time if you don't yet update some of the information listed above.
Also, if you leave California but only plan to be away for part of the year, that may not change your residency status. This could be an important factor for those moving out of the state but who still plan to travel in the state. You can learn more about residency status in the FTB's Guidelines for Determining Residency Status.
California taxes all of your income while you're a resident, then generally taxes only California-source income once you become a nonresident. For equity compensation, what counts as California-source income depends partly on the type of equity you hold and when the taxable event occurs.
Here's where things get even more nuanced. RSUs, ISOs, and NSOs don't all follow the same tax rules when you move out of California.
The key differences are:
When each type of equity creates taxable income
What period California looks at when deciding how much of that income is connected to work performed in the state
You may also owe capital gains tax when you eventually sell shares acquired through RSUs or stock options. That's separate from any compensation income created when RSUs vest or options are exercised.
To illustrate this a bit better, let's break it down by equity type and how those are taxed by California if you leave the state.
| Equity type | Main tax trigger | What happens if you move out of California? | Key thing to watch |
|---|---|---|---|
RSUs | Ordinary income when taxable/vested, then capital gains when sold | California may still tax the portion tied to work performed in California before the taxable event | Grant-to-vest workday allocation |
ISOs | Possible AMT at exercise, then tax when sold | California may still tax California-source compensation or AMT-related income depending on timing and where services were performed | AMT and qualifying vs. disqualifying disposition |
NSOs | Ordinary income at exercise, then capital gains when sold | California may tax the portion of exercise income tied to services performed in California | Grant-to-exercise workday allocation |
ESPPs | Generally taxed when shares are sold | California may tax the compensation portion attributable to the period you worked in California | Purchase/offer period and qualifying vs. disqualifying disposition |
Beyond when each type becomes taxable, your equity may have further details to consider if you're considering leaving California.
RSUs are different from ISOs and NSOs because they are not stock options that need to be exercised. Instead, once they vest, they are now shares that you own. But you will owe tax when they vest and again when you later sell.
However, you also need to consider whether you have single-trigger or double-trigger RSUs.
Single-trigger RSUs will be taxed immediately upon vesting. These are common for those at public companies.
Double-trigger RSUs aren't taxed at vesting until there is a second trigger, oftentimes an IPO or an acquisition. These are more common at later-stage, private startups so that employees don't owe taxes at vesting on shares they can't yet sell.
But both types of RSUs are taxed similarly upon vesting and selling.
When vested:
At vesting, RSUs are subject to ordinary income tax. This is true for both single-trigger and double-trigger RSUs. For single-trigger RSUs, the tax is determined by the share price at the time of vesting. For double-trigger RSUs, the tax is determined by the share price when the second trigger happens. Again, this is often an IPO, but could also be an acquisition or another type of exit.
If your RSUs become taxable after you become a California nonresident, the Allocation Ratio can be used to determine what portion of that income is still California-source. If you're still a California resident when the income is recognized, California generally taxes the full amount.
When selling:
RSUs are subject to capital gains tax when selling, based on the difference between the share price when you vest and the sale price. If you sell them while a resident of a different state, you will not owe tax in California.
ISOs can trigger tax both when exercised (purchased) and when you sell them. You generally don't owe regular federal income tax when exercising ISOs, although the exercise can trigger Alternative Minimum Tax (AMT). You may also be able to avoid some taxes when exercising your ISOs, unlike NSOs.
When exercising:
Exercising ISOs can trigger Alternative Minimum Tax (AMT). The amount you owe depends on the difference between the 409A valuation at the time you exercise and the strike price. AMT is an alternate tax system, and the benefits are that you may be able to reclaim that tax in the future, especially after you sell any of the shares.
Not all states have AMT, but California does. If you exercise stock options granted to you in California after you leave the state, any AMT you owe would be based on the Allocation Ratio explained above.
Check if the state you're moving to has AMT, such as Connecticut, Colorado, and Minnesota, because you may also owe AMT there.
When selling:
Depending on how long you hold onto your exercised ISOs before selling, the shares will be considered either a "qualified disposition" or a "disqualified disposition."
If you hold your shares for at least 2 years after they were granted and 1 year after exercising them, they are considered a qualifying disposition and are subject to long-term capital gains tax for federal tax purposes, which generally has lower rates than ordinary income tax. California, however, taxes capital gains at the same state income tax rates as ordinary income. The taxable amount is the difference between the strike price and the amount you sell them for.
Capital gains tax is only paid to the state where you are currently a resident, meaning you would likely not owe California but only the state where you reside at the time of the sale.
If you sell any shares before those holding two requirements are met, they will be considered a disqualifying disposition. In that case, some of the gain may be treated as ordinary income, while any additional gain may be treated as capital gain. If you're a California nonresident at the time of the sale, California may still tax the ordinary income portion to the extent it is connected to services you performed in California.
At Secfi, we help startup employees understand and plan around their equity. AMT comes up frequently with clients because it can be difficult to estimate without support. Most online calculators for equity and AMT are overly simplistic, so we set out to solve that by building Maeve.
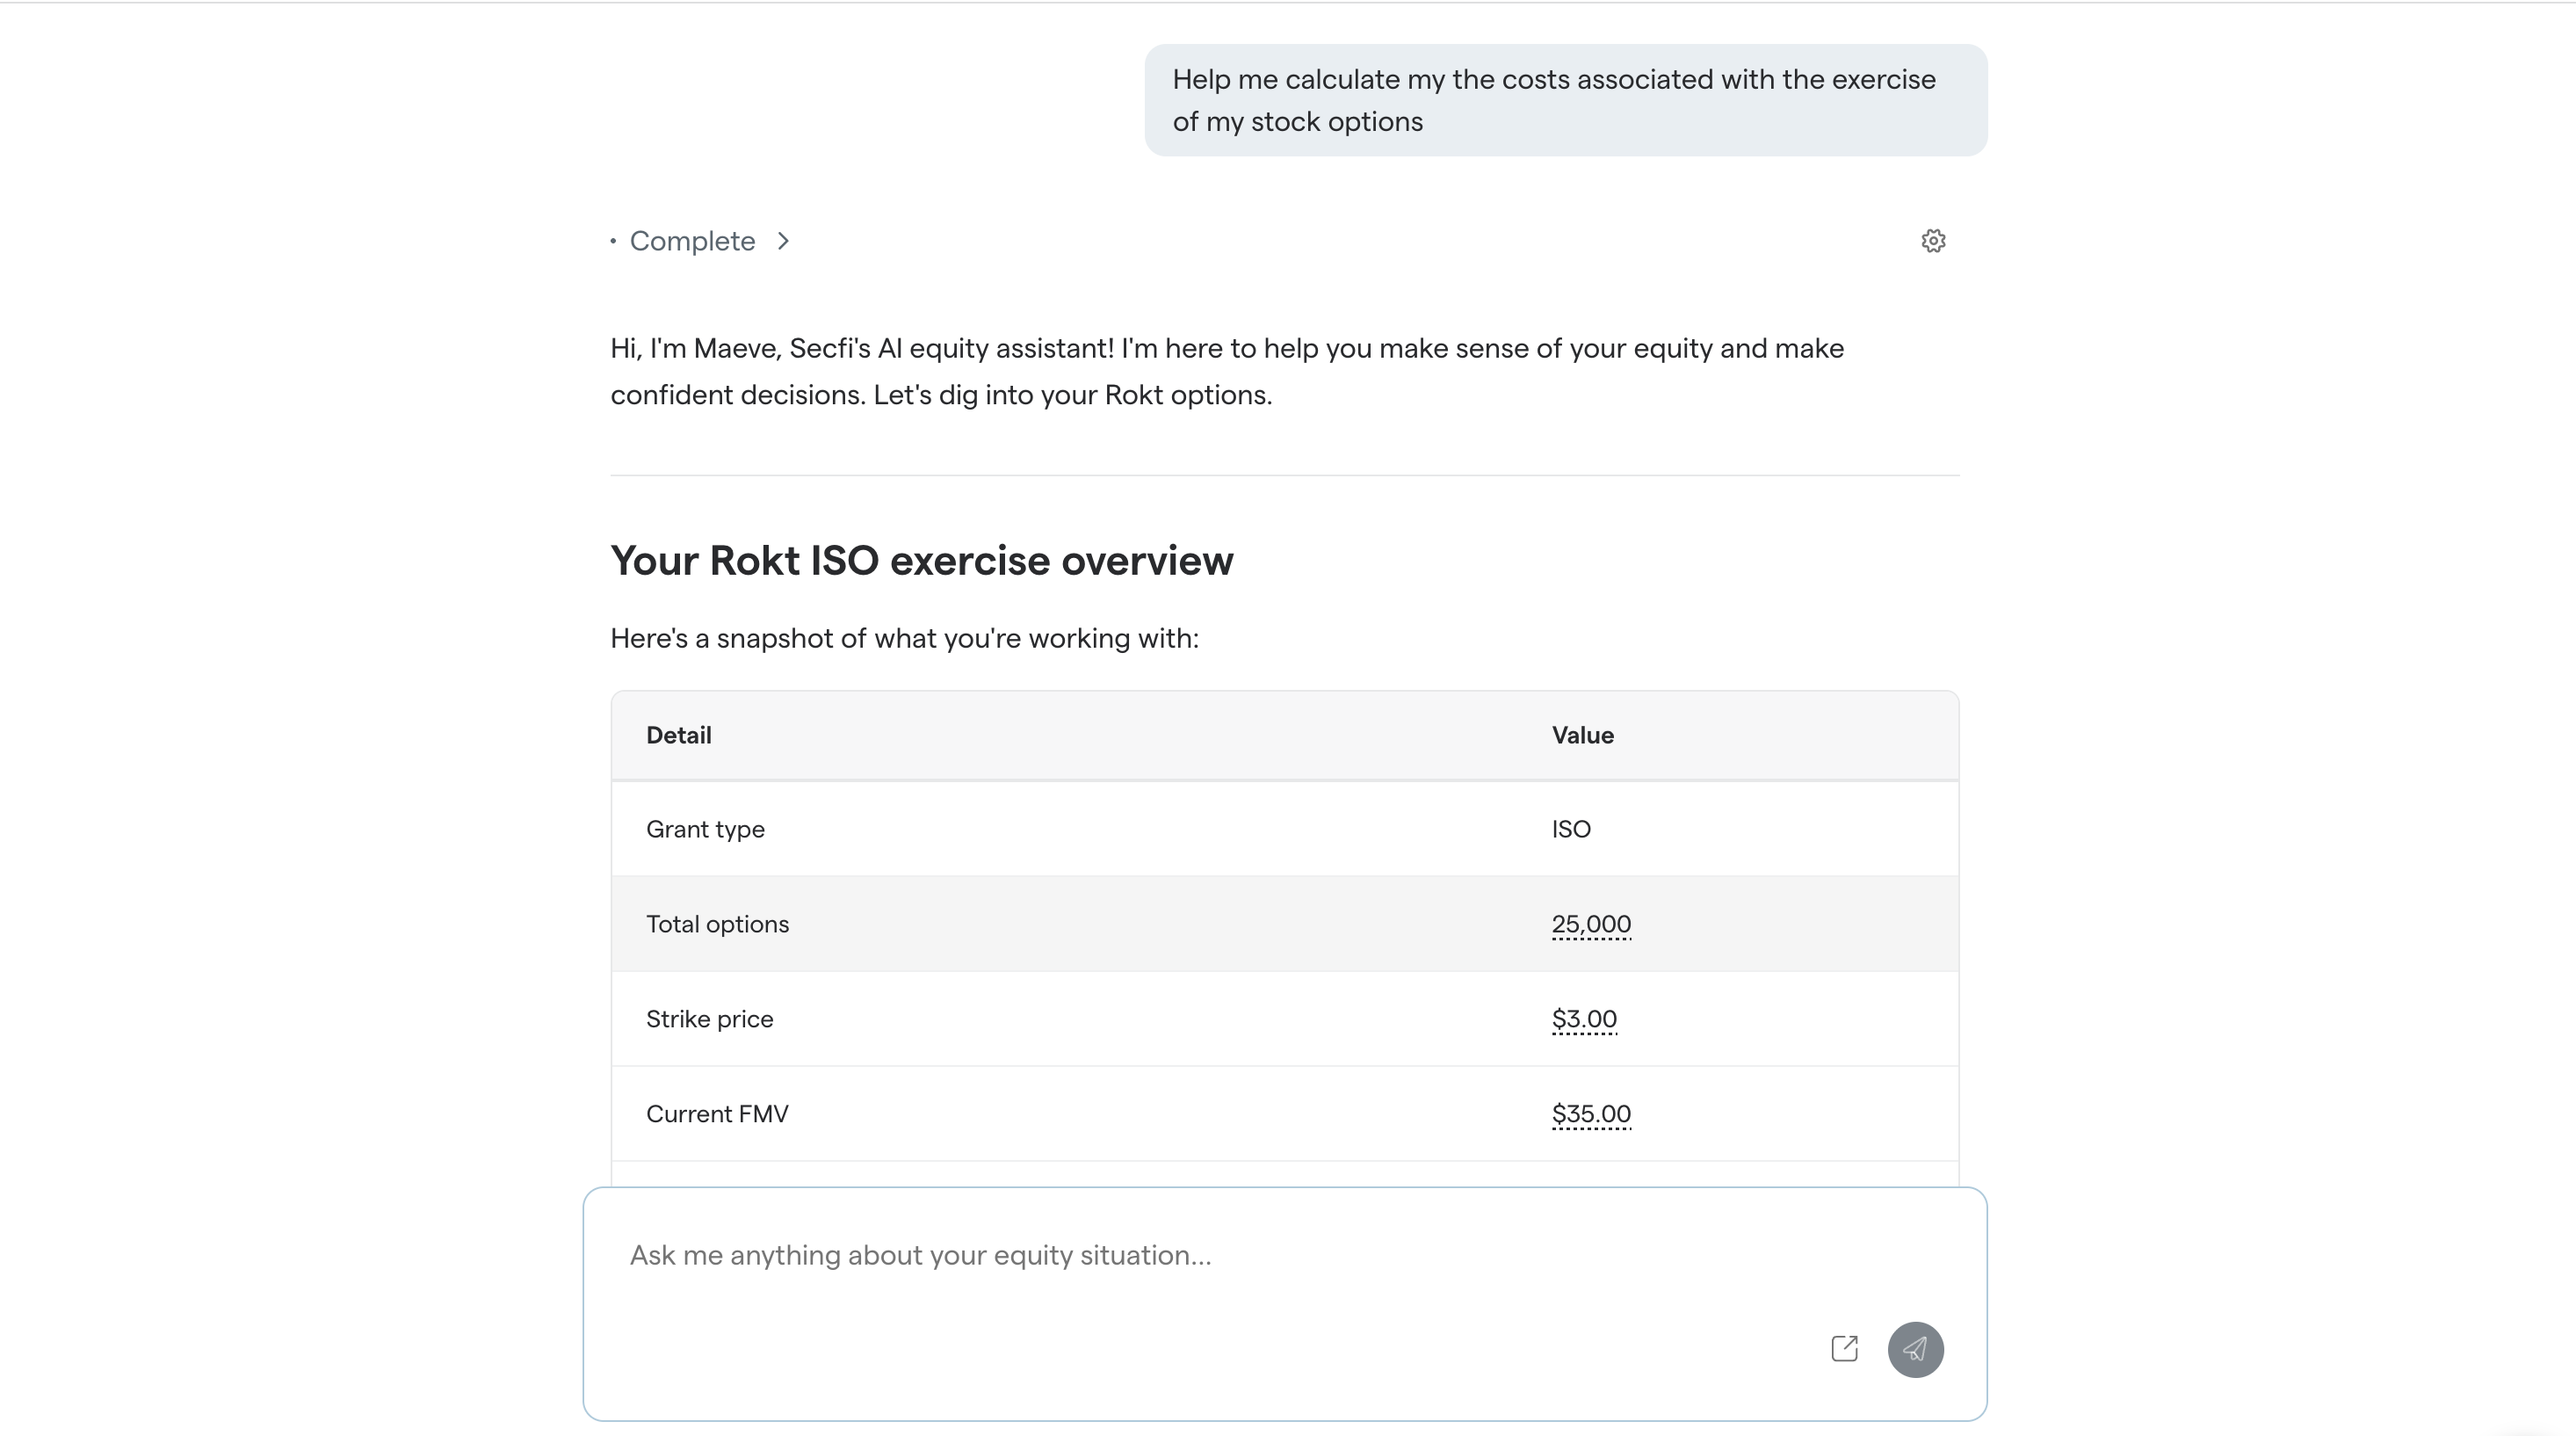
For illustrative purposes only. Actual results may vary and there is no guarantee of any particular outcome.
You can connect your Carta account or enter your information manually, then ask Maeve questions about your AMT and equity. If exercising makes sense but the upfront cost is difficult to cover, Secfi also offers non-recourse financing. If your company is eligible, we can help fund your exercise and associated taxes, without putting your own cash and personal assets at risk. As always, you should also ask a tax professional regarding your particular circumstances.
Like ISOs, Non-Qualified Stock Options (NSOs) are taxed both at exercise and when you sell shares. However, NSOs are subject to ordinary income tax at exercise, unlike ISOs which can trigger the AMT.
When exercising:
Like ISOs, NSOs are taxed on the spread between the 409A (Fair Market Value), at the time of exercise and the strike price. Unlike ISOs, this "bargain element" as it's called (or sometimes referred to as "phantom income") is subject to ordinary income tax on your W2, rather than AMT.
Any income tax you owe California would be subject to the Allocation Ratio.
When selling:
The tax you owe is determined by the difference between the 409A at the time you exercised and the sale price.
If you exercised shares as a California resident, but later sell them as a resident in a new state, the sale would be subject to capital gains tax only in your current state. Meaning, the sale would not be subject to California tax.
An ESPP is a program that allows employees to purchase company stock at a discounted rate, often as high as 15%. You only pay tax when you sell any stock you've purchased.
When selling:
When you sell ESPP shares, you may have both ordinary income and capital gain or loss.
Like ISOs, the shares will be considered either a qualifying or disqualifying disposition at the time of the sale, depending on how long you hold them. To be considered a qualifying disposition, you must hold them for at least one year from when you purchased them, and two years from the ESPP original offer date (similar to a grant date).
If you lived in California during the period you were eligible to purchase shares but sell after you moved away, you will pay California tax based on the number of days you worked in the state.
For ESPPs, the Allocation Ratio uses a different period than RSUs. California generally looks at your workdays from the grant or offering date to the exercise or purchase date when determining how much of the ordinary income portion is California-source. Any capital gain is generally sourced to the state where you live when you sell the shares.
Even if you move away but return to California, you'll generally be subject to California tax on income you recognize while you're a California resident, regardless of where the income was sourced. That can include income from ISOs or NSOs you exercised, RSUs that become taxable, or ESPP shares you sell after returning to the state.
For example, if you return to California before selling shares and recognize a capital gain while you're a resident, California will generally tax that gain. The Allocation Ratio discussed above is primarily relevant when determining how much compensation income is California-source while you're a nonresident.
However, California may offer you a tax credit if the same income is also taxed by another state, depending on the states involved and your circumstances.
Secfi helps startup employees from California and across the US plan and act on your equity. Our team knows the stress of moving across borders, on top of dealing with equity.
We've supported over 62,000 startup employees and executives trying to figure out what to do with their RSUs and other forms of equity.
Here's why people at Stripe, Snowflake, and DoorDash use Secfi to plan their equity.
Maeve is Secfi's purpose-built AI equity assistant, designed to take your personal situation and risk profile into account. You can model scenarios relating to your equity and taxes to feel more informed for different situations.
For example, if you're planning to move out of California, you could use Maeve to compare how different vesting and exercise dates affect your equity. This helps you identify the questions worth discussing with a tax professional before you move.
For illustrative purposes only. Actual results may vary and there is no guarantee of any particular outcome.
Unlike many calculators and AI tools, we designed Maeve so you can look under the hood and check its assumptions and calculations.
Here's more about Why we built Maeve.
Beyond taxes, when you're moving you may also need to think about liquidity for a new home, and how that impacts your equity and other investments.
You might be trying to decide between optimizing for tax efficiency or choosing the simplest path so you can focus on the move. Fortunately, those goals aren't always mutually exclusive. Our Wealth team specializes in helping startup employees understand and make these decisions.
They can help you build a plan that takes your stock options, RSUs, ESPP shares, taxes, liquidity needs, and wider finances into account, including more complex situations such as multiple grants or moving between states with different tax rules. Their fiduciary duty also requires them to act in your best interests, and they don't work on commissions.
Secfi doesn't replace your tax preparer, but our advisors specialize in equity compensation and can help with questions that a generalist advisor may not regularly handle. As our client Austin put it:
"The value I'm getting is the tax planning, and the holistic approach. It's like all these things that I felt like were missing from a traditional financial advisor."
Testimonials are specific to an individual Client's experience and may not be representative of all Clients. Unless otherwise indicated, Clients offering a Testimonial do not receive compensation and their statement does not present a conflict of interest.
If you're considering exercising your options at any point, Secfi's Wealth team can also refer you to our equity strategists to discuss non-recourse financing.
If you decide to exercise your stock options, Secfi can help you explore non-recourse financing.
Non-recourse financing can cover some or all of your exercise costs and associated taxes, so you don't owe any cash upfront. There are no monthly payments. And if your shares become worthless or your company doesn't have a successful exit, the financing provider generally can't pursue unrelated personal assets like your home or savings.
If your company does exit successfully, you still participate in the potential upside. At that point, Secfi is repaid according to the terms of your financing agreement, which can reduce your eventual proceeds. Not every startup or employee will be eligible, but if you are, non-recourse financing can give you another way to exercise while preserving more liquidity around a move.
We've provided over $800 million in financing to startup employees, more than any other non-recourse financing provider with this model. Learn more about How Secfi financing works – our business model explained.
And if considering selling your shares outright, Secfi can also help you explore a secondary market sale.
Leaving California can complicate your equity decisions. Secfi can help you model your options, understand the tax and liquidity tradeoffs, and build a plan around your move so you can focus on everything else.
Try Maeve if you just want to run the numbers for different scenarios, or speak with our team if you'd like further support.
RSUs are generally taxed as ordinary income when they become taxable, and you may owe capital gains tax later when you sell the shares.
If you move out of California before your RSUs become taxable, California may still tax the portion of the income connected to work you performed in the state. For RSUs, that usually means looking at your California workdays during the grant-to-vest period compared with your total workdays during that same vesting period.
Your new state may also tax the income, depending on its rules. That can create a risk of double taxation, although credits may be available in some situations.
Maeve, Secfi's AI equity assistant, can help you review your grant details, vesting schedule, and different timing scenarios before you speak with a tax professional.
No. California does not impose a tax simply because you move out of state.
However, moving does not automatically end your California tax obligations. Once you become a nonresident, California can still tax California taxable income, including certain equity compensation tied to services you performed in the state.
For example, RSU taxation can still involve California income tax after you move if part of the grant-to-vest period relates to work you performed in California. The same general idea can apply to stock options and ESPPs, although the sourcing rules and taxable events differ.
RSUs can create both ordinary income tax and capital gains tax.
When your RSUs become taxable, their value is generally treated as compensation and included in income. If you are a California resident at that time, California generally taxes the full amount as part of your California taxable income.
If you have already moved out of state, California may still tax the portion connected to services you performed in California during the relevant vesting period.
If you later sell the shares, any increase or decrease in value after the taxable event generally creates a capital gain or loss. California taxes capital gains at the same state income tax rates as ordinary income for residents.
If you have multiple RSU grants or are planning a move, Secfi's Wealth team can help you understand how your equity fits into your broader financial plan, while a tax professional can advise on your specific filing obligations.
Generally, California cannot tax certain retirement income once you are a nonresident, including qualifying distributions from pensions and retirement plans that are protected under federal law.
That is different from equity compensation. RSUs, stock options, and ESPPs can still create California-source income after you move if the compensation is tied to work you performed in California.
So if you are moving out of state and have both retirement assets and startup equity, the tax implications can be very different. It is worth looking at each type of income separately rather than assuming the same California state taxes apply to everything.
The tool shown here uses artificial intelligence and is for illustrative purposes only and not necessarily indicative of future results and there is no guarantee that similar results can be achieved. The information provided by the tool is not professional advice and is not intended by Secfi, Inc., its affiliates, and Secfi representatives, to be deemed as investment, legal, tax or other professional advice or recommendations of any kind, or to form the basis of any decision to do or to refrain from doing anything. Secfi does not review the accuracy or completeness of the information provided to us within the tool.