Startup stock options explained: A guide for employees
18 min
0 result
John’s a Director at Secfi, helping founders, executives and employees navigate equity compensation and access to liquidity through his expertise in finance.
Startup stock options give you the right to buy shares in your company at a fixed price. If the company grows and those shares become more valuable, your options could eventually be worth a significant amount.
But their value isn't guaranteed, and the number of options in your offer letter doesn't tell you much on its own. If you've just joined a startup, it's worth taking the time now to understand what you were actually given.
Most startups use stock options to give employees a stake in the company's future, but your potential outcome depends on details such as your strike price, vesting schedule, option type, company valuation, and what happens before you eventually sell.
In this guide, we'll cover:
How startup stock options work
What you need to understand about the stock options in your offer or grant
What happens after you receive startup stock options
How you can pay for a stock option exercise
Secfi helps you make sense of your startup stock options
Why Amanda used Secfi to understand and exercise her startup stock options while minimizing risk
Want help understanding your startup stock options? Maeve, Secfi's AI equity assistant, can help you review your grant details and model different exercise, tax, and exit scenarios.
Startup stock options give you the right to buy a set number of company shares at a fixed price, known as your strike price or exercise price.
Startups often use stock options as part of employee compensation because they can conserve cash while giving you a financial stake in the company's future. That shared upside helps align employee incentives with the company's long-term success.
They usually follow a simple path:
You receive a stock option grant in your offer letter. Your grant tells you how many options you have, your strike price, and the relevant terms.
Your options vest over time. Most startup employees earn their options gradually according to a vesting schedule.
You decide whether to exercise. Exercising means paying the strike price to turn your vested options into shares you actually own, and it may also create a tax bill. You can fund an exercise with your own cash, or sometimes with non-recourse financing.
You become a shareholder. If you exercise, you own shares in the company rather than options to buy them. Those shares are usually still private and may be difficult to sell right away.
You wait for a chance to sell. Because startup shares are usually private, you may need to wait for an IPO, acquisition, tender offer, or secondary sale before you can turn them into cash.
Here's a basic example, but remember to check with an expert for your own situation:
Say you have the option to buy 10,000 shares for $2 each. Exercising all of them would cost $20,000 before taxes. If you later sell those shares for more than $2 each, you could make a gain. But if the company falls in value or never reaches a liquidity event, the shares could be worth less than you paid or even become worthless.
The important thing is that 10,000 options alone doesn't tell you whether you have a valuable grant. That's why your next step should be to look at the actual terms of your offer or grant.
If you've just received a startup job offer, the equity section may look detailed while still leaving out information you'll eventually need to make decisions about your stock options.
Here's an anonymized example from a startup offer we've reviewed. The numbers and identifying details have been changed for privacy:
"Subject to the approval of the Company's Board of Directors, you will be granted an option to purchase 15,550 shares of the Company's Common Stock. The exercise price per share will be determined by the Board of Directors when the option is granted. The option will vest over four years, with 25% vesting after 12 months of continuous service and the remainder vesting in equal monthly installments over the following 36 months."
At first glance, this tells you quite a bit. You know the size of the grant, that it has a standard four-year vesting schedule, and that the strike price will be set when the grant is approved.
But it still doesn't tell you enough to evaluate what those 15,550 options could mean financially.
For example, the strike price hasn't been set yet. It doesn't tell you whether the options are ISOs or NSOs, what the company's current 409A valuation is, what percentage of the company the grant represents, or what happens to your vested options if you leave.
And those details can materially change what the grant means for you.
If you're still trying to figure out the details, you can share any of your relevant equity information with Maeve, our free AI equity assistant. It's purpose-built to help you understand and act on your equity, and can help you model scenarios and see what further questions you need to ask based on your grant information.
For illustrative purposes only. Actual results may vary and there is no guarantee of any particular outcome.
You don't necessarily need to act right away, but it's worth spending some time to understand your vesting schedule sooner rather than later, especially if your company allows early exercise. The following can affect what your options are worth, what they cost to exercise, and how much time you have to make a decision.
"Vesting" is a financial term that describes what you need to do to earn your stock options. The most common schedule is four years with a one-year cliff: 25% of your options vest after your first year, with the remainder vesting monthly over the following three years. But always double-check, as your grant may be different.
You generally can't exercise unvested options unless your company allows early exercise. And you don't need to wait for all your options to vest to exercise. In some cases, exercising on an annual basis can be a good way to reduce your tax bill.
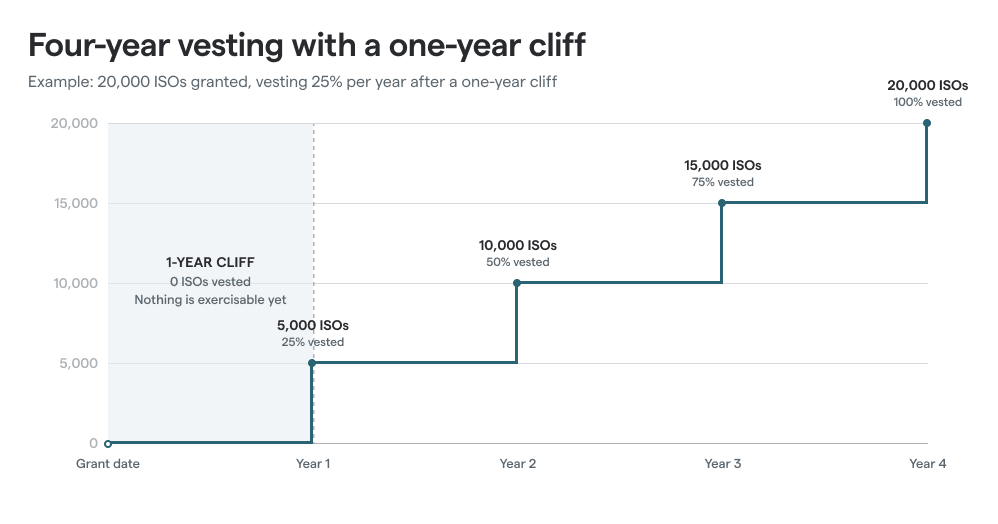
For illustrative purposes only. Actual results may vary, and there is no guarantee of any particular outcome.
Read more: What is a stock option vesting schedule?
A 409A valuation is used to determine your strike price and the fair market value (FMV) of the company's common stock. If the valuation rises while your strike price stays the same, the spread between the two will increase, which may affect the taxes due when you exercise.
Typically, equity is granted in one of three forms: ISOs, NSOs, and RSUs. Each incurs its own taxation rules, changing the real cost to exercise.
And the tax cost can become significant. Especially if your company's value has risen substantially since your options were granted. This is because the spread between your strike price and fair market value can be taxed.
Incentive stock options (ISOs) are generally available only to employees and can qualify for more favorable tax treatment if you meet certain holding requirements. If you exercise any amount of ISOs, you'll need to prepare for the alternative minimum tax (AMT).
This is an alternative system that ensures high earners pay enough in tax, with the major difference being that your ISO spread is taxable, usually at 26% or 28%.
You'll work out both your normal tax and AMT, then pay whichever is higher. Having a larger AMT bill is called "triggering AMT", and that amount can be multiple times higher than your exercise price alone.
Non-qualified stock options (NSOs) can be granted more broadly and generally create ordinary income tax when you exercise based on the spread between your strike price and the share value at that time. If you're in California, that can be as high as 50%.
RSUs aren't stock options at all. They're a different type of equity compensation that typically gives you shares once certain vesting conditions are met, rather than the right to buy shares at a strike price. Usually, your company will sell off a certain amount of your RSUs automatically when they vest to cover the tax. You'll then only receive the net amount.
Read more: What is the $100k rule? A guide to the ISO/NSO split
Exercising means paying your strike price to buy the shares as well as the accompanying tax bill. Deciding if/when to exercise can involve weighing up real tradeoffs.
Whether or not you exercise, there are risks to consider. For instance, earlier exercise can sometimes reduce future tax costs, but it also means putting money into private company stock that may never become liquid.
Alternatively, waiting to exercise means keeping your personal capital for other investments, but risking a significant future tax bill if your company has a successful exit. If you leave the company, you also might miss out on the opportunity to exercise at all, which we've gone into more detail on below.
To navigate the decision, ask yourself:
How confident are you in the startup's ability to successfully exit?
How much will it cost to exercise your stock options?
Are there tax benefits to exercising now, rather than later?
Read more: When should you exercise your stock options?
Depending on your grant, you may have a limited period after leaving to exercise vested options before they expire. Check both the option expiration date and your post-termination exercise window, rather than assuming you have the commonly cited 90-day window.
Read more: Should you exercise stock options after leaving your company?
You don't need to make every decision when you receive the grant. But understanding these milestones early gives you more time to compare your options before a tax bill, exercise cost, or deadline forces the issue.
Exercising startup stock options can require more cash than people expect, especially once taxes are included. If you decide exercising makes sense, there are a few ways to cover the cost or create liquidity around the decision.
| Option | How it works | Main tradeoff |
|---|---|---|
Cash on hand | You use your own savings to cover the strike price and any taxes due. | Simple, but you're putting your own cash into a private company investment that may become illiquid or lose value. |
Non-recourse financing | A financing provider covers some or all of your exercise costs and related taxes, with repayment tied to the agreement and a future liquidity event. | You'll pay fees and typically share some potential upside, but unrelated personal assets aren't put on the line. |
Traditional loan | You borrow the money needed to exercise and repay the lender according to the loan terms. | You generally still owe the debt and interest even if the company performs poorly or never exits. |
Secondary sale | If you already own private shares, you may be able to sell some through a company tender offer or secondary transaction and use the proceeds toward exercising other options or covering related taxes. | A sale can take time, may require company approval, and means giving up some potential future upside on the shares you sell. |
There isn't one best way to fund an exercise. The right approach depends on how much cash you're comfortable investing, your view of the company, your tax situation, the time you may have to wait for liquidity, and how much financial risk you're willing to take.
Secfi can help you understand, plan, and act on your equity. Here's why employees at companies like Stripe, DoorDash, and Reddit trust us:
Once you know the details of your grant, our free AI equity assistant Maeve can help you see how different choices could play out using your own equity information.
Maeve is built to help with equity decisions. General-purpose LLMs can give different answers to the same equity question depending on how you phrase it, because they're predicting an answer rather than running a dedicated calculation engine. Maeve uses Secfi's tax and equity models for the underlying math, then shows what was calculated versus what came from the AI itself.
That gives you a more useful starting point than trying to piece together your equity and related taxes across several calculators or spreadsheets. Maeve also synthesizes live data from secondary markets and 409A updates to provide a current view of your portfolio's potential value.
You can connect your Carta account or enter your grant details manually, then compare scenarios such as exercising now, waiting, or exercising only part of your options. Maeve can help you estimate exercise costs, taxes, AMT exposure, and different potential exit outcomes.
For illustrative purposes only. Actual results may vary and there is no guarantee of any particular outcome.
Non-recourse financing can help cover the cost of exercising stock options and associated taxes without using unrelated personal assets as collateral. It means you can still participate in potential upside if your company continues to grow.
Secfi has provided over $800 million in financing to startup employees. You don't have to make monthly payments, and no one can come after your home or car if your company fails and the shares become worthless.
If there's a successful exit, you repay according to the terms of your financing agreement. If there isn't a successful exit, Secfi absorbs the loss. Non-recourse financing also doesn't typically impact your debt-to-income ratio, which can be helpful if you're looking to secure a mortgage or line of credit for something else in the future.
It's also not all or nothing; you can use some of your cash to exercise your options, and non-recourse financing to exercise the rest. Our equity strategists can help you figure out if you're eligible, and what makes sense for your situation.
We can also help you explore a secondary sale and negotiate on your behalf if you'd prefer to sell your eligible shares.
Your stock options can eventually become a significant part of your finances, which means decisions around exercising, selling, or holding them can affect much more than the grant itself.
Secfi Wealth's financial advisors specialize in working with startup employees and executives. They can incorporate your private-company equity into planning around taxes, AMT, diversification, cash reserves, home purchases, and other financial goals.
Their specialist knowledge can be useful when a traditional financial plan doesn't fully account for private shares, tender offers, concentrated startup equity, or the tax consequences of exercising stock options.
When Amanda joined a fast-growing startup, she said she had "no idea what equity was when I accepted my offer." As she learned more, she realized the tax implications of her stock options might be a lot higher than she'd first thought. Her company had a meeting about options, and "That meeting set me off on this little bit of a panic."
Her biggest concern was risk. Exercising with cash meant putting a significant amount of money into private company stock, and she didn't want to use a bank loan or put her family's savings on the line. She began searching and reading online to understand the full scope of her tax implications.
"Secfi was one of the only websites I could find that could give me accurate calculations of AMT", she said.
Amanda used Secfi's tools to better understand her potential AMT bill, then chose non-recourse financing to help cover the cost of exercising. She said the non-recourse structure was one of the most important factors in her decision because she wouldn't owe Secfi if the company never had a successful exit.
Read Amanda's story here: Why a startup employee used Secfi to buy her stock options.
Testimonials are specific to an individual Client's experience and may not be representative of all Clients. Unless otherwise indicated, Clients offering a Testimonial do not receive compensation and their statement does not present a conflict of interest.
Startup stock options can be valuable, but the outcome depends on far more than the number of options in your grant. Your strike price, vesting schedule, taxes, company valuation, and eventual liquidity all shape what those options could mean for you.
The earlier you understand those moving parts, the more time you have to make deliberate decisions instead of reacting to a deadline later.
Want help figuring out what your startup stock options? Try Maeve or get in touch with our team.
They can be, but the number of options in your grant doesn't tell you their value on its own. Your strike price, the company's value, your percentage ownership, dilution, taxes, and eventual sale price all affect the outcome.
If the company grows and you can eventually sell your shares for more than you paid to exercise them, your options may generate a gain. But private company shares can also lose value or never become liquid.
Secfi's AI equity assistant, Maeve, can help you model different company values, exercise costs, taxes, and exit outcomes using your own grant details.
There's no single "good" number of stock options because option counts vary widely between companies.
A grant of 50,000 options at one startup could represent less ownership than 5,000 options at another. If you're comparing an offer, look at your percentage ownership, strike price, vesting schedule, company valuation, and potential dilution rather than judging the grant by option count alone.
If you already have your grant details, Maeve can help you organize those numbers and model what different outcomes could mean financially.
The $100,000 rule applies to incentive stock options (ISOs). Under current U.S. tax rules, only up to $100,000 worth of stock underlying your ISOs can first become exercisable in a calendar year and still receive ISO treatment.
Any amount above that limit is generally treated as non-qualified stock options for tax purposes. The calculation is based on the fair market value of the shares when the options were granted.
If you're unsure how the rule applies across multiple grants or vesting dates, Secfi's equity tools and Maeve can help you model your option schedule, although a tax professional should confirm how the rules apply to your situation.
Stock options and restricted stock units (RSUs) work differently, so one isn't automatically better.
Stock options give you the right to buy shares at a fixed strike price and can provide more upside if the company grows significantly. RSUs generally become shares once their vesting and any other applicable conditions are met, so you usually don't need to pay a strike price to acquire them.
The better fit depends on factors such as the company's stage, potential upside, tax treatment, liquidity, and how much risk you're comfortable taking. Maeve can help you compare different equity scenarios using the details of your compensation package.
You generally keep vested options but lose unvested options when you leave, although the exact rules depend on your equity plan and grant agreement.
Your vested options may also become subject to a post-termination exercise window. Some plans use a 90-day window, but you shouldn't assume yours does. Check your option agreement, so you know exactly how long you have to exercise before the options expire.
If you're considering leaving, Maeve can help you estimate what it may cost to exercise by a particular date. And if exercise costs are the main barrier, Secfi may be able to help with non-recourse financing, depending on eligibility.
They can create significant wealth if you join a successful company, receive a meaningful grant, exercise at a favorable cost, and eventually sell your shares at a much higher price.
But there's no guarantee. Many startups never reach a successful exit, and taxes, dilution, exercise costs, and the price you eventually sell at can all reduce the final value of your equity.
Secfi and Maeve can help you model best-case, middle-case, and downside scenarios so you can understand the potential range of outcomes before making a decision.
The tool shown here uses artificial intelligence and is for illustrative purposes only and not necessarily indicative of future results and there is no guarantee that similar results can be achieved. The information provided by the tool is not professional advice and is not intended by Secfi, Inc., its affiliates, and Secfi representatives, to be deemed as investment, legal, tax or other professional advice or recommendations of any kind, or to form the basis of any decision to do or to refrain from doing anything. Secfi does not review the accuracy or completeness of the information provided to us within the tool.