What is a stock option vesting schedule?
20 min
0 result
Frederik is the CEO and Co-Founder of Secfi. The leading online platform where we help founders, executives and employees of fast growing technology companies better manage their equity through Wealth Management, Equity Planning and Equity Financing. In addition, he runs Secfi Capital, Secfi's institutional investment arm focused on investing in late stage private companies.
A stock option vesting schedule tells you when you earn the right to exercise your stock options. It’s a way for your employer to incentivize you to stay with the company.
But once you learn the basics about your private stock options, the harder questions usually start. Taxation, exercising, deadlines, cliffs… how do you put all of that together and decide what to do?
We often find these questions pile up so much that startup employees feel overwhelmed and put decisions off altogether.
But waiting too long can limit your options. Exercising may become more expensive as your company’s valuation rises, or you could find yourself with a short window to make a decision if you leave your company.
In this article, we'll answer common questions about stock option vesting schedules and bring in other important tips and considerations.
We’ll cover:
What is a stock option vesting schedule?
Common types of stock option vesting schedules
Important things to consider as your stock options vest
How Secfi can help you plan around your vesting schedule
How Amanda turned vested options into a plan with Secfi
If you want help making sense of your stock option vesting schedule, ask Maeve, Secfi’s free AI equity assistant.
A stock option vesting schedule determines when you earn the right to exercise your stock options. Vesting schedules are designed to encourage employees to stay with a company and contribute over time, rather than receiving the full value of an equity grant upfront.
Once options vest, you generally have the right to exercise them and buy shares at your strike price. Vesting itself doesn’t mean you own the shares yet. You only become a shareholder after you exercise the options.
Cliff vesting is a type of schedule where none of your options vest until you’ve reached a certain milestone, known as the “cliff.” Afterward, options typically vest incrementally, often monthly or quarterly.
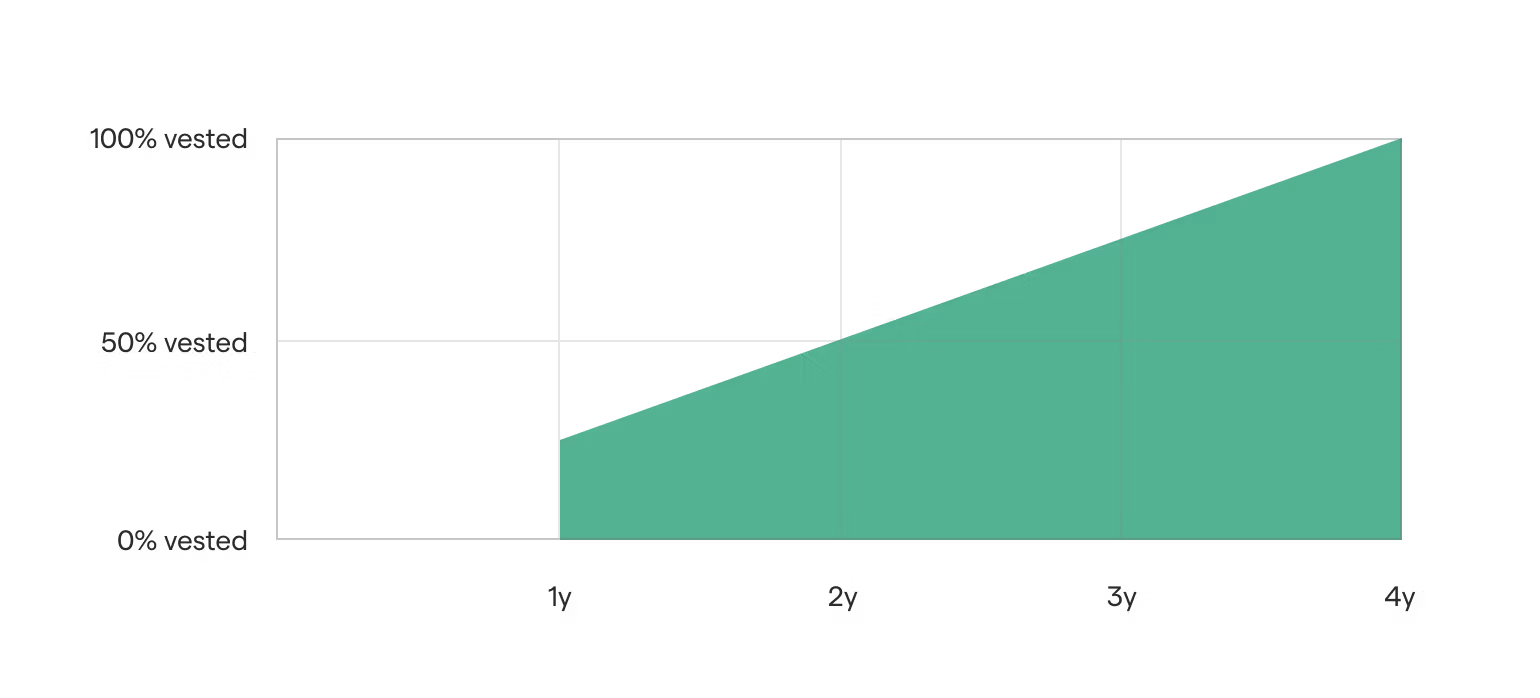
One of the most common arrangements you’ll see is a four-year vesting schedule with a one-year cliff:
During the first year, none of your options are vested.
After one year, 25% of your options vest immediately.
The remaining 75% typically vest monthly over the next three years until your full grant is vested.
For illustrative purposes only. Actual results may vary, and there is no guarantee of any particular outcome.
In this case, if you leave before the 12-month mark, you’ll forfeit 100% of your options and walk away with zero equity. That cliff gives employees an incentive to stay through at least the first 12 months, since leaving before then usually means forfeiting the entire unvested grant.
Then on your first anniversary, 25% of your options vest. But you still need to exercise them to become a shareholder. Every month after that, you get 1/48th of your options until they’ve all vested at the four-year mark.
At that point, 100% of your options are vested, and you can exercise as many or as few as you choose or are able, subject to your grant’s exercise and expiration terms.
You don’t have to wait until all of your options are vested before exercising. Once a portion has vested, you can generally exercise some or all of that vested amount, subject to your grant terms.
Here’s an example, but check with a tax professional for your own situation.
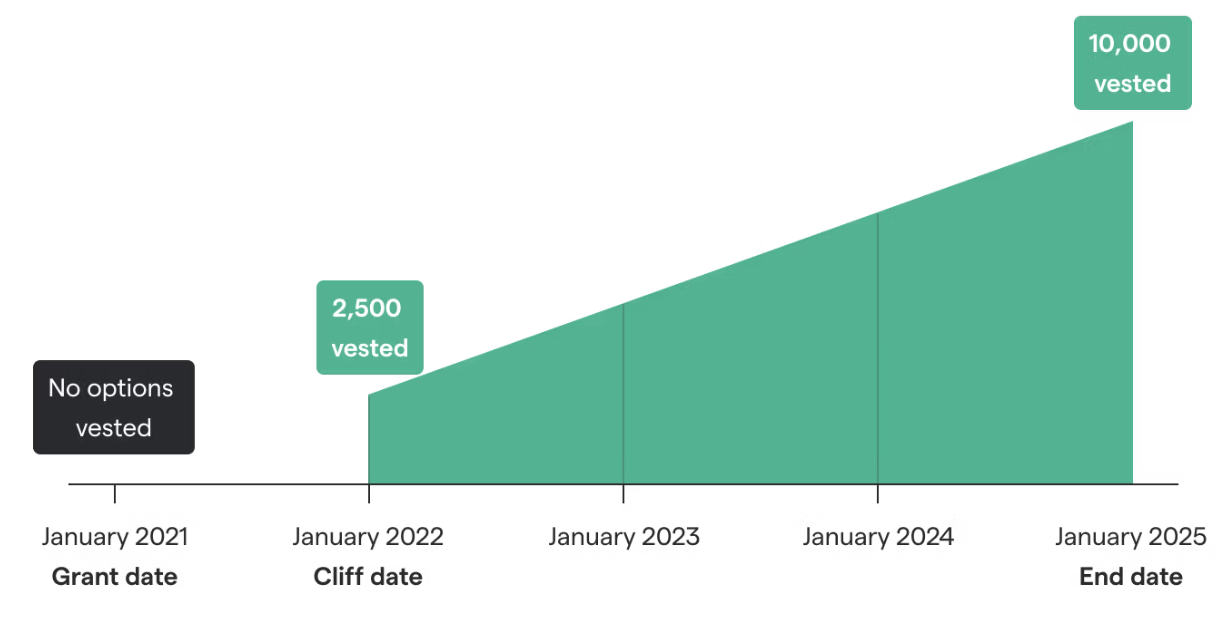
Let’s say Startup Inc. grants you 10,000 stock options on a four-year vesting period with a one-year cliff. Under this schedule, 2,500 would typically vest after your first year. The remaining 7,500 would then vest over the following three years.
Here’s how that would play out:
For illustrative purposes only. Actual results may vary, and there is no guarantee of any particular outcome.
While a four-year vesting schedule with a one-year cliff is standard for most startup employee grants, alternative schedules are more commonly seen in executive compensation and may sometimes be negotiated, such as removing the cliff.
Your exact schedule should be listed in your stock option grant agreement. It may fall under any of these categories:
| Vesting schedule | How it works | Where you may see it |
|---|---|---|
Time-based vesting with a cliff | None of your options vest during the cliff. A portion vests once you reach it, followed by regular monthly or quarterly vesting. | Common for startup employees, often over four years with a one-year cliff |
Time-based vesting without a cliff | Options start vesting gradually from the beginning of the vesting period. | Less common, but may be used for some employee grants |
Performance-based vesting | Options vest after you or the company meet specified performance goals rather than simply after a certain amount of time. | More commonly used for executives or grants tied to particular goals |
Hybrid vesting | Vesting depends on a combination of time and performance requirements. | Customized compensation arrangements, particularly for senior employees |
Sometimes, but usually only if your grant agreement or equity plan includes an acceleration provision. In most cases, once your vesting schedule is set, you can’t simply choose to make your options vest sooner.
Accelerated vesting allows some or all of your unvested options to vest earlier than originally scheduled if specified conditions are met.
You may see acceleration provisions connected to an acquisition or other change in control at your company. Depending on your agreement, acceleration can be:
Single-trigger: One event, such as an acquisition, triggers accelerated vesting.
Double-trigger: Two events generally need to happen, such as the company being acquired and your employment subsequently being terminated under specified circumstances.
Acceleration isn’t automatic just because your company is acquired. Check your grant agreement and equity plan to see whether you have an acceleration provision and exactly what triggers it.
Some companies offer early exercise, which means you can exercise stock options before they’ve vested.
That’s different from simply exercising vested options sooner. With early exercise, you’re buying shares that are still subject to your vesting schedule. If you leave before those shares vest, your company may have the right to repurchase the unvested portion, depending on your agreement.
If you early exercise unvested shares, an 83(b) election may also be relevant. An 83(b) election lets you choose to be taxed based on the value of the shares when they’re transferred to you rather than as they vest. The filing deadline is generally 30 days from the date the shares are transferred to you, so this is one area where timing matters a lot.
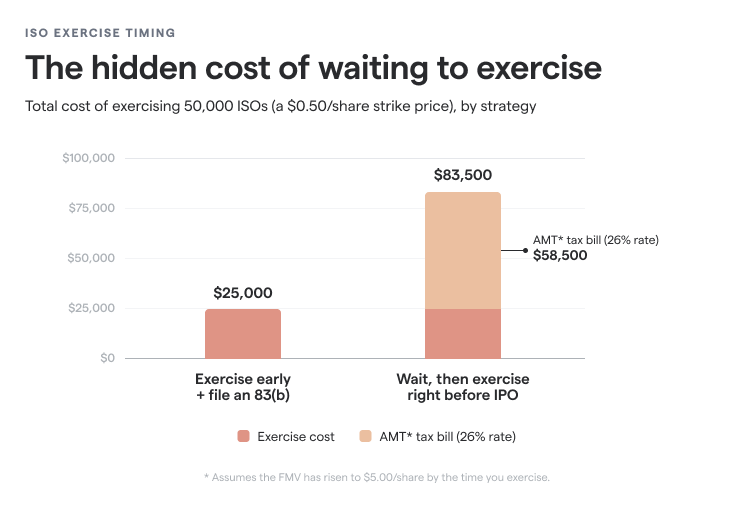
Early exercise with the 83(b) can be used as a way to reduce your tax obligation from exercising. That’s because you are usually taxed on the difference between your strike price and the fair market value (FMV) at the time of exercise.
If you do an early exercise, the FMV is likely still the same, or only slightly higher than your strike price, meaning little to no taxable spread.
Here’s a simplified example: suppose you have 50,000 ISOs with a $0.50 strike price. Exercising while the FMV is still close to the strike price would cost $25,000 to exercise. If the FMV later rises to $5 per share, the larger spread could create an estimated AMT bill of about $58,500, bringing the total exercise cost in this example to $83,500.
That doesn’t mean early exercise is always the better choice. You’re putting cash at risk sooner, and the shares may never become liquid or increase in value.
For illustrative purposes only. Actual results may vary, and there is no guarantee of any particular outcome.
As more of your options vest, you have more choices to make. As you add in more factors and your circumstances change, it can get complicated quickly.
At Secfi, we help startup employees understand and act on your equity. We built Maeve, our free AI equity assistant, to help you navigate different decisions based on your actual equity and tax data. You can use Maeve to model the considerations below using your own grant and tax details.
For illustrative purposes only. Actual results may vary, and there is no guarantee of any particular outcome.
Vesting gives you the right to exercise your options, but it doesn’t mean you have to exercise them immediately or all at once.
Let’s say 5,000 of your 10,000 options are currently vested. Depending on your grant terms, you might:
Exercise all 5,000
Exercise 1,000 now and leave the rest unexercised
Exercise a portion each year
Wait until you have more information about the company or more cash available
A staged approach can be useful if exercising the entire vested amount would require more cash or create more tax exposure than you’re comfortable with. For example, exercising fewer ISOs in a given year may help you stay below the point where AMT is triggered, depending on your income, spread, and other tax factors.
Read more about strategies that may help reduce AMT.
This is different from early exercise, which specifically means exercising before your options vest. Here, we mean exercising already-vested options sooner rather than later.
If your company’s 409A valuation rises while your strike price stays the same, the spread between the two grows. Depending on your option type, that larger spread can increase the taxes associated with exercising.
For example, for a theoretical Snowflake employee, estimated exercise costs increased from about $53,000 when the assumed share value was $30 to more than $472,000 when the share price reached $250. That’s just an example, and your own situation will vary, but it demonstrates how taxes can add up.
Exercising sooner can also start the long-term capital gains clock earlier. For NSOs, hold more than one year after exercise. For ISOs to get favorable treatment, hold more than one year after exercise and more than two years after grant. Otherwise, you’ll face the higher short-term capital gains rate, or even your ordinary income tax rate.
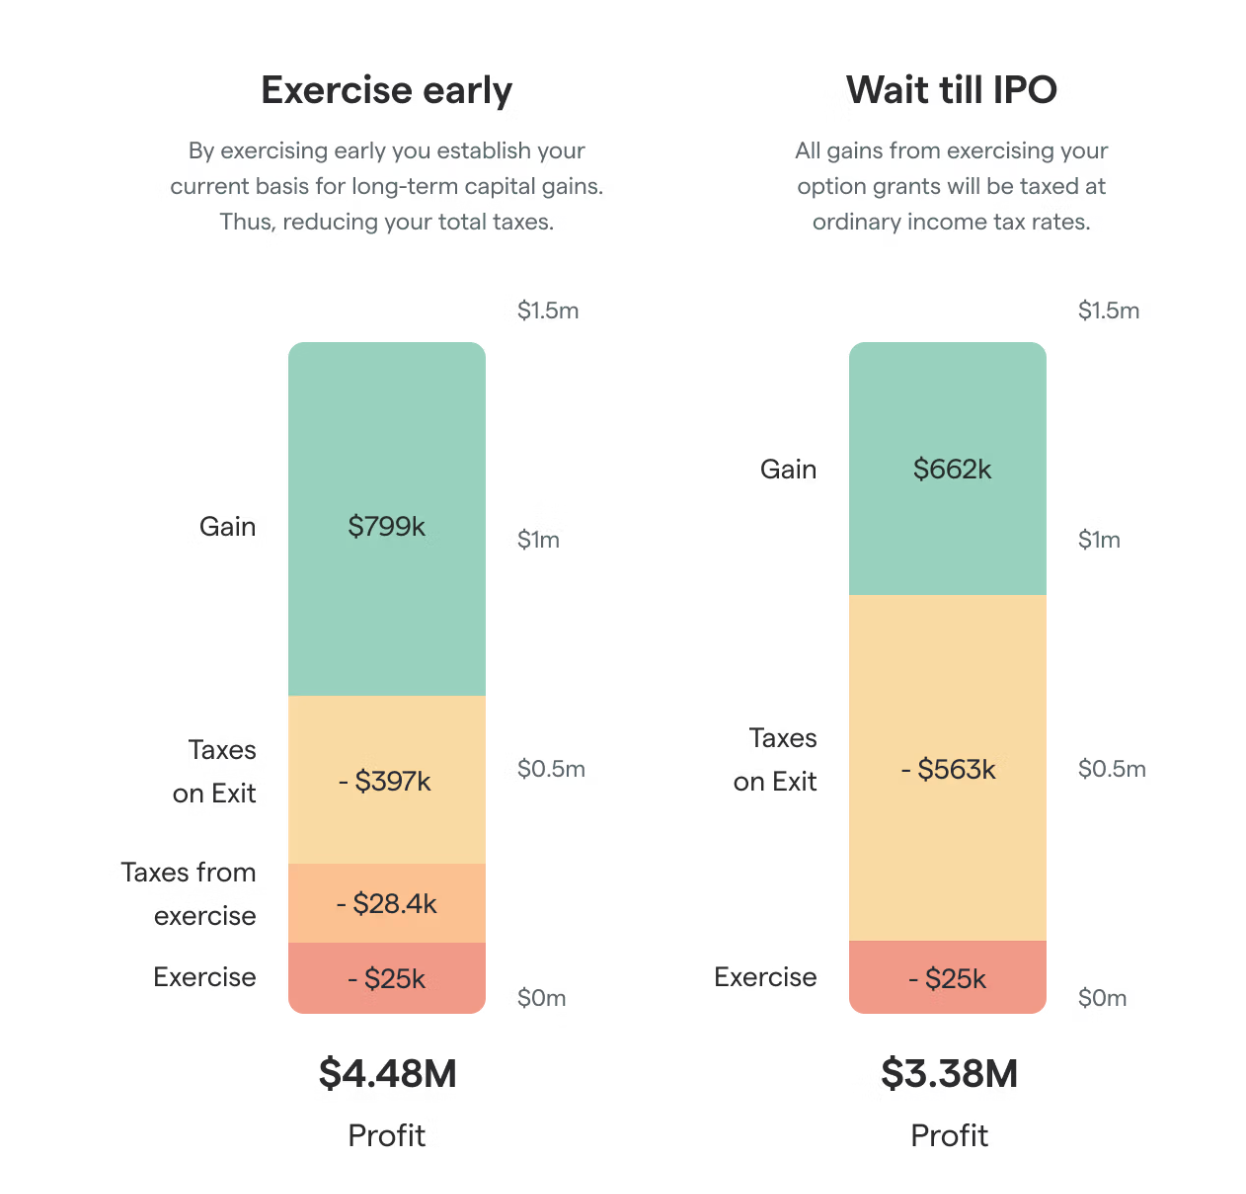
For illustrative purposes only. Actual results may vary, and there is no guarantee of any particular outcome.
Waiting can still be the right choice in some cases. For example, you may want to reduce the amount of time your money is tied up in illiquid shares, or spend more time getting to know the company before investing.
The tax consequences depend heavily on whether you have incentive stock options (ISOs) or non-qualified stock options (NSOs).
With ISOs, exercising and holding the shares can create an adjustment for alternative minimum tax (AMT). The larger the difference between your strike price and the fair market value (FMV) at exercise, the larger that adjustment can be.
With NSOs, the spread between the strike price and fair market value at exercise is generally treated as ordinary income.
That means two employees with the same number of vested options and the same strike price could face very different tax outcomes depending on the type of options they hold.
For ISOs in particular, you may choose to exercise fewer shares in a given year to manage AMT exposure rather than exercising your entire vested balance at once.
There’s also a $100,000 annual limit for ISOs to keep in mind. If the fair market value of the shares underlying your ISOs that first become exercisable in a calendar year exceeds $100,000, the portion above that threshold is generally treated as an NSO for tax purposes.
If exercising your vested options makes sense, the next question is how you’ll cover the cost. That can include the strike price, taxes due at exercise, or both.
Exercising private-company stock options is an investment decision with some unusual risks. Even if you’re excited about the company’s growth, it’s still important to consider if you’d invest the same amount of money in a public company or index fund.
You’ll also likely be exchanging cash for private shares that you can’t immediately sell. Pre-IPO shares are generally illiquid; liquidity events such as an acquisition or tender offer are usually outside your control, and secondary sales may depend on company approval and the terms of your grant.
Some employees use their own savings. Others look at financing, which generally falls into two broad categories:
Traditional financing: A personal loan, home equity loan, line of credit, or other recourse debt can give you the cash to exercise. The catch is, you’re personally responsible for repaying it. You may owe monthly payments regardless of what happens to your company, and your other assets or credit could be affected if you can’t repay.
Non-recourse financing: This is specifically structured around the value of your equity. Rather than relying on your personal assets for repayment, the financing is generally repaid from a future liquidity event like an IPO. If the shares ultimately have little or no value, the provider takes on more of that downside risk.
For example, imagine exercising your options would cost $150,000 between the strike price and taxes. You could fund the full amount yourself, borrow it through traditional financing and take on the repayment obligation, or use non-recourse financing and preserve more of your personal cash while accepting the financing terms.
That doesn’t mean financing is automatically the better choice. You’re still giving up some future upside through the financing terms, so it’s worth comparing the cost of financing against other options.
If you leave your company, your vesting usually stops on your final day of employment or another date specified in your plan documents. Any options that haven’t vested by then are typically forfeited.
Your vested options are a different story. You may still be able to exercise them after leaving, but only for a limited period known as your post-termination exercise window. That window varies by company and grant, so don’t assume you automatically have 90 days.
For example, imagine you were granted 10,000 options on a four-year schedule and leave after two years with 5,000 vested:
The 5,000 unvested options would typically be forfeited.
The 5,000 vested options may remain exercisable for whatever period your grant agreement allows.
If you don’t exercise before that deadline, you could lose the vested options too.
This can turn leaving a job into a much more urgent financial decision.
That’s why it’s worth checking your vesting schedule and post-termination exercise terms before resigning if possible. Confirm how many options will be vested on your departure date, your exercise deadline, the estimated exercise cost, and any tax consequences.
The choice you make at your one-year cliff may look very different two years later.
Useful moments to reassess include:
A new funding round or 409A valuation
A large portion of your grant vesting
A promotion or new equity grant
Considering leaving the company
An acquisition or IPO becoming more likely
Changes in your income, tax situation, or cash needs
Our founders at Secfi had to leave shares on the table because they didn’t have access to the guidance and funding they needed to exercise their options. Today, we’ve helped over 62,000 startup employees at 90% of U.S. unicorns make decisions around vesting, exercising, taxes, and liquidity.
Here’s why employees at companies including Stripe, SpaceX, and Anthropic choose to work with Secfi.
Maeve is our purpose-built AI equity assistant. It can help you make sense of your grant details and compare different paths as more of your options vest.
For example, you could compare:
Exercising only the options that are currently vested
Exercising part now and more in a later tax year
Waiting until a future date
How a higher 409A valuation could affect estimated exercise costs and taxes
How different exercise amounts could affect AMT exposure
Unlike predictive-text-based AIs, we built Maeve based on rigorous calculator engines developed over the years based on our experience at Secfi. You can check its assumptions and model different scenarios as your circumstances change.
It’s easy to set up and can connect directly to your Carta account or extract information from any documents you upload. That makes recommendations personalized to your situation, instead of generalized examples.
For illustrative purposes only. Actual results may vary, and there is no guarantee of any particular outcome.
For eligible employees, Secfi offers non-recourse financing that can help cover the cost of exercising stock options and associated taxes without putting unrelated personal assets on the line. There are no monthly payments, and you only need to pay via a portion of your equity if your company has a successful exit. You keep ownership of your shares throughout the process.
Another benefit of non-recourse financing is that it doesn’t typically impact your debt-to-income ratio, which makes it easier to take out mortgages or other loans.
We’ve provided over $800 million in financing to help startup employees own their options and participate in potential upside, more than any other company of this type.
To be able to offer non-recourse financing, we generally work with employees at later-stage companies. Ideally, you hold equity in a company expected to exit within a few years with a $1B+ valuation. We encourage you to submit a request so our team can review your eligibility.
If you want a financial advisor in your corner, Secfi’s Wealth team can help you look at your vested options alongside taxes, liquidity, concentrated private-company stock, and other financial goals. Many advisors understand how to invest in public companies, but working with startup equity comes with its own set of nuances that can make a difference in your outcomes.
Our team works with stock option vesting schedules every day and can provide guidance on the specific complexities of taxes and exercising. Even if you haven’t made any money from your shares yet, having a financial advisor can help you plan to make the most of your stock options as they vest.
The financial advisors on our Wealth team have a fiduciary duty to act in your best interests, and they only work on fees. That means they only recommend products or services that align with your situation, not for a commission.
When Amanda joined a fast-growing software company, her stock options largely sat in the background while they vested.
When she finally started digging into the details, she realized that capital gains tax and AMT were more complicated than she realized. She was worried about missing out on something important in a potentially high-stakes financial decision.
But it was worth figuring out. She knew if she made the right decisions, “it meant building wealth for me and the family I’m building.”
Amanda chose to exercise her ISOs and used Secfi’s non-recourse financing to help cover the cost. She felt that Secfi gave “the fairest offer and the best resource in my journey.” Amanda said she exercised partly for the potential AMT benefit, and that the non-recourse structure was one of the most important factors in her decision because she didn’t have to risk her cash directly.
Read more: Why a startup employee used Secfi to buy her stock options.
This case study is an illustration of our capabilities provided to an individual client. Client results may vary and there can be no guarantee of similar results. It is not known whether the client approves or disapproves of Secfi Advisory Limited or its affiliates as a whole. Unless otherwise indicated, Clients offering a Testimonial do not receive compensation and their statement does not present a conflict of interest.
Your stock option vesting schedule tells you when your options become exercisable. What you do after that depends on variables including taxes and your company’s valuation. But most importantly, it depends on your financial situation and how much risk you’re comfortable taking.
If you want help comparing different paths, ask Maeve to model scenarios around your vested options, exercise timing, and potential tax impact.
And if you’d rather talk it through with someone, get in touch with Secfi to speak with our team.
When a stock option vests, you generally gain the right to exercise it and buy shares at your strike price. Vesting doesn’t automatically give you vested shares. You usually need to exercise the option first.
Your exact stock vesting terms depend on your company’s stock option plans and grant agreement. Some companies use a standard cliff vesting schedule, while others may use graded vesting, milestone-based vesting, or other structures as part of an employee’s broader equity compensation.
If you want to see how many of your options are vested and what exercising them could cost, you can ask Maeve, Secfi’s AI equity assistant, to help you review your grant details and model different exercise scenarios.
Usually, vesting alone doesn’t mean you can immediately sell anything. When stock options vest, they become exercisable. You typically need to exercise them first and receive shares before you can potentially sell those shares.
Whether you should exercise or sell depends on factors such as your strike price, current fair market value, taxes, company outlook, available cash, and whether there’s actually a market for the shares.
Private-company shares can be difficult to sell, and a secondary sale may require company approval. In some cases, you may choose to hold vested options, exercise only part of them, or wait for a future liquidity event instead.
Maeve can help you compare different paths using your own equity details, and Secfi’s team can help if you want to talk through exercise timing, financing, or a potential secondary sale.
The $100,000 rule applies to incentive stock options (ISOs). In general, if more than $100,000 worth of shares underlying your ISOs first become exercisable in a single calendar year, the excess is treated as non-qualified stock options (NSOs) for tax purposes.
The $100,000 amount is based on the fair market value of the shares when the options were granted, not their value when they vest or when you exercise them.
This can become relevant if your compensation package includes a large ISO grant, multiple overlapping grants, or accelerated vesting. Secfi can help you model how different portions of your grant may be treated and what that could mean for your taxes.
Neither is automatically better. RSUs, or restricted stock units, and stock options work differently and may suit different companies, stages, and employees.
With RSUs, you generally receive shares once the vesting conditions are met, subject to the terms of the grant. With stock options, vesting gives you the right to buy shares at a set strike price, which means you still need to decide whether and when to exercise.
Stock options may offer more upside if the company grows substantially after the grant date, but they also require you to put money at risk when you exercise. RSUs typically don’t require an exercise payment, but their tax treatment and liquidity considerations are different.
If you’re comparing different forms of equity compensation, look at the full compensation package, including salary, number of units or options, vesting schedule, strike price, taxes, and the company’s stage.
The tool shown here uses artificial intelligence and is for illustrative purposes only and not necessarily indicative of future results, and there is no guarantee that similar results can be achieved. The information provided by the tool is not professional advice and is not intended by Secfi, Inc., its affiliates, and Secfi representatives, to be deemed as investment, legal, tax, or other professional advice or recommendations of any kind, or to form the basis of any decision to do or to refrain from doing anything. Secfi does not review the accuracy or completeness of the information provided to us within the tool.