What is a stock blackout period? What to do before, during, and after
18 min
0 result
Mike’s a CPF® at Secfi. He specializes in helping clients make the most of their stock options and integrate equity compensation into their broader financial plans.
You’ve been thinking about exercising your stock options for months. Maybe you were waiting for a bonus to hit, trying to get comfortable with the tax bill, or telling yourself you’d deal with it after the next funding round.
Then your company announces a stock blackout period. Meaning, you can’t exercise your options, sell shares, or make other stock transactions until the blackout ends. That could take a few days or even months in some cases. And while you’re stuck waiting, the numbers might keep moving.
A new funding round could lead to a higher 409A valuation.
Your exercise could get more expensive.
Your potential tax bill could grow.
If you’re leaving the company, an already-tight exercise deadline can make the situation even more stressful.
Stock blackout periods can feel especially hard because the timing is largely out of your hands. But understanding why they happen, what restrictions may apply, and what could change while you wait can help you make a plan before your next window opens.
In this article, we’ll cover:
How does a stock blackout period work?
How long does a stock blackout period last?
How a blackout period can affect your exercise costs
What to do before, during, and after a stock blackout period
How Secfi can help you plan around a stock blackout period
Not sure what a stock blackout period could mean for your equity? Ask Maeve, Secfi’s free AI equity assistant, to help you understand and plan your next move.
A stock blackout period temporarily limits certain transactions involving company stock. Depending on the company and the reason for the blackout, you may be unable to buy or sell shares, exercise stock options, or make other equity-related transactions until the restriction is lifted.
Ideally, your company should communicate what the blackout covers and, when possible, how long it’s expected to last. But even a relatively short blackout can matter if you were planning to exercise soon, especially if your company’s fair market value changes before the window reopens.
Blackout periods usually happen around events where sensitive company information, a changing valuation, or a major transaction could affect company stock or your ability to transact.
A funding round can trigger a temporary blackout on stock option exercises. Private companies may pause exercises while a financing round is underway, particularly if the transaction could lead to a new 409A valuation.
A public company may impose a blackout period before an earnings announcement. You might be restricted from trading shares when you could have access to financial results or other information that hasn’t been released publicly yet to reduce insider trading risk.
An IPO can bring additional restrictions on employee stock transactions. You may face a blackout during parts of the IPO process, followed by other restrictions such as an IPO lock-up period after the company goes public.
Mergers, acquisitions, and other major company events can also lead to blackout periods. If employees have access to information that could materially affect the value of the company or its stock, certain transactions may be restricted until that information becomes public or the transaction is completed.
There’s no standard length for a stock blackout period. It could last a few days, several weeks, or longer depending on what triggered it and when the company is able to lift the restriction.
For public companies, regularly scheduled trading blackouts around earnings often last around two weeks to a month. Blackouts tied to funding rounds, 409A updates, IPOs, or acquisitions can be harder to predict because they may depend on when a transaction or valuation process is completed.
| Cause of blackout | What determines when it ends |
|---|---|
Earnings announcement | Usually when financial results have been released and the company’s trading window reopens. |
Funding round | When the financing reaches a stage where the company is comfortable reopening stock option exercises or other transactions. |
409A valuation update | When the new valuation has been finalized and implemented. |
IPO | When the company’s IPO-related restrictions are lifted. Employees may still face a separate post-IPO lock-up period. |
Merger or acquisition | Often when the transaction or other material information becomes public, or when the company determines the restriction is no longer necessary. |
Your company’s equity or legal team should be your source of truth for the exact dates. And if there isn’t a firm end date yet, that uncertainty is worth factoring into any plans to exercise your options.
Usually, if your company has placed stock option exercises under a blackout, you’ll have to wait until the restriction is lifted before you can exercise.
The exact rules depend on your company and the type of blackout, so check with your equity or legal team to understand what applies to you.
The frustrating part is that waiting can sometimes increase your exercise costs.
If the blackout happens around a funding round or 409A update, your company’s fair market value (FMV) could increase before you’re able to exercise again. Your strike price stays the same, but a higher FMV can increase the taxable spread when you exercise, potentially leaving you with a larger tax bill.
At Secfi, we provide education and funding around startup equity. Our data shows how quickly exercise costs can climb as a startup raises new rounds of funding.
If we take a hypothetical example, the cost to exercise $10,000 worth of pre-seed ISOs increased 3,360% between pre-seed and Series C, based on industry-average valuation growth for a previous year.
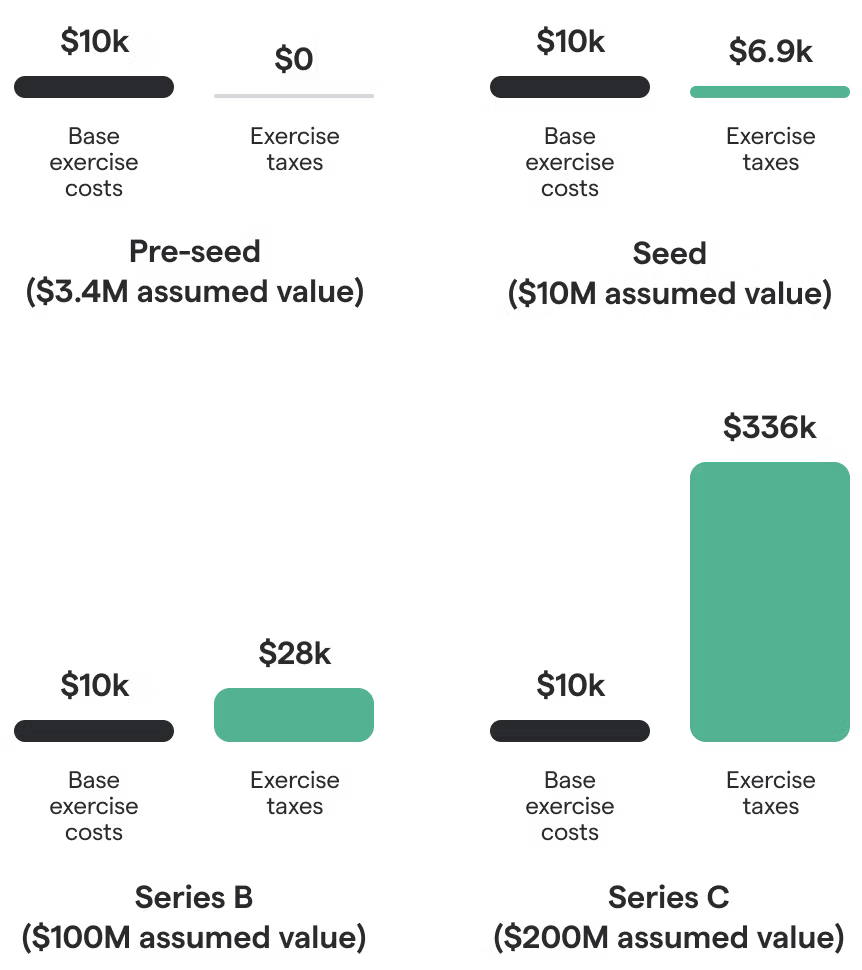
For illustrative purposes only. Actual results may vary and there is no guarantee of any particular outcome.
That doesn’t mean every funding round will increase your exercise cost by the same amount. But it illustrates why timing is key: if a blackout overlaps with a new funding round or 409A valuation, the cost of exercising may look very different by the time the window reopens.
Here’s a simplified example. Always check with a tax professional before making decisions for your own situation.
Imagine you have options with a $5 strike price and your company’s current 409A valuation is $10 per share. If a funding round happens during the blackout and the new 409A comes back at $15, the spread between your strike price and FMV has doubled from $5 to $10 per share.
Depending on whether you hold ISOs or NSOs and your individual tax situation, that larger spread could mean significantly more tax when you exercise.
Not necessarily. Exercising private-company stock can mean putting substantial money at risk before you know whether, when, or at what price you’ll eventually be able to sell your shares. Your tax situation, exercise cost, confidence in the company, and personal finances all matter.
If you know a blackout or major company event may be coming, understanding both the potential cost of waiting and the risks of exercising sooner can help you make a more informed decision.
If exercising makes sense but you’re uncomfortable taking on the full financial risk yourself, non-recourse financing is another option. Secfi provides equity education and funding to thousands of startup employees. Our non-recourse financing can help eligible employees cover exercise costs and taxes without requiring repayment from personal assets if your shares lose value. You can keep potential upside, instead of alternatives like selling shares for cash right away.
A blackout can leave you with fewer choices in the moment, which makes planning around the window especially valuable.
As you work through the steps below, Maeve, Secfi’s free AI equity assistant, can help you model different scenarios and understand how changes in your company could affect your equity. You can use Maeve before a blackout to explore your options, while you’re waiting to see how the numbers might change, and after the blackout to reassess your next move.
For illustrative purposes only. Actual results may vary and there is no guarantee of any particular outcome.
If you have reason to believe a funding round, IPO, 409A update, or other major company event is approaching, get a clear picture of your equity before your ability to transact changes.
Know your current numbers. Check your strike price, current 409A valuation, number of vested options, and estimated cost to exercise.
Understand the potential tax bill. The spread between your strike price and FMV can affect the taxes associated with exercising, so model what an exercise could cost under the current valuation.
Check your deadlines. If you’re considering leaving your company or have another exercise deadline approaching, find out how a potential blackout could affect your timing.
Consider what could change. Model scenarios with a higher FMV so you can see what waiting might mean for your exercise cost and taxes.
Ask what restrictions may be coming. Your company may not be able to share every detail of an upcoming event, but your equity or legal team can clarify current policies and how employees will be notified of a blackout.
Once a blackout begins, first figure out exactly what you can and can’t do. Not every blackout restricts every type of equity transaction.
Confirm which transactions are restricted. Find out whether the blackout applies to exercising options, buying or selling shares, or all of the above.
Ask whether there’s an estimated end date. Some blackout periods have a defined window, while others depend on a transaction or valuation process being completed.
Keep an eye on your exercise deadlines. Don’t assume a blackout automatically extends an expiration or post-termination exercise window. Ask your company what happens if the two overlap.
Run the numbers while you wait. If a new 409A valuation is likely, compare what exercising could look like at different FMVs so you aren’t starting from scratch when the blackout lifts.
When the blackout ends, don’t assume you should simply pick up the plan you had before it started. First, check what changed.
Confirm the new FMV. If your company completed a new 409A valuation, see whether the value of common stock increased or decreased.
Recalculate your exercise cost and potential taxes. A change in FMV may significantly change the economics of exercising your options.
Revisit your overall equity strategy. Consider your remaining time to exercise, your view of the company’s prospects, your personal finances, and when liquidity might realistically happen.
Explore ways to fund an exercise if needed. If exercising still makes sense but the cost is now difficult to cover yourself, options such as non-recourse financing may help you exercise without taking on the full personal financial risk.
If you leave your job while your company is in a blackout period, it can get complicated because you might also be facing a post-termination exercise window.
Check with your stock plan administrator or equity team as soon as possible. In some cases, a company may extend the exercise window to account for the blackout, but you shouldn’t assume that will happen automatically.
If you hold ISOs, timing matters for another reason. Under current U.S. tax rules, ISOs generally need to be exercised within three months after your employment ends to retain ISO tax treatment. Options exercised after that point may be treated as NSOs instead.
Stock blackout periods can create a frustrating combination of uncertainty and limited time to act. Secfi helps you understand how to plan around major company events, including providing non-recourse funding that can cover taxes. We’ve helped over 55,000 startup employees and executives with our tools, team, and funding.
And if you’re on the other side of the equation, preparing your company for a blackout period, Secfi can help your employees understand what’s happening before their ability to transact changes. Our equity education programs for startup teams cover stock options, taxes, exercise scenarios, and planning around major events such as an IPO or exit.
Here's why employees at companies like Gusto, Google, and Canva work with Secfi:
Maeve, Secfi’s AI equity assistant, can help you understand your stock options and run different scenarios that are more advanced than the DIY spreadsheet you might have already started. You can also double-check its assumptions and inputs based on our years of developing tools for startup employees, making it more tailored to equity planning than a general-purpose calculator or LLM.
You can connect the Secfi platform to Carta, which Maeve can then access, upload your grant documents, or enter your details manually to get started. Then, it’s up to you to decide how you’ll use it for stock blackout periods and any other equity situations you want to model.
Ask questions and you’ll get answers specific to your unique situation, based on our years of providing tools for the nuances of equity-specific situations like AMT and acquisitions. Compare how changes in your company’s 409A valuation could affect your exercise cost and potential taxes, and compare exercising at different points in time.
Maeve can also help you compare different exercise funding scenarios, such as using your own cash or choosing financing.
For illustrative purposes only. Actual results may vary and there is no guarantee of any particular outcome.
If you decide you want to exercise but the cost of your options and taxes is difficult to fund yourself, Secfi’s non-recourse financing may help eligible employees cover those costs.
Unlike a traditional loan, non-recourse financing is secured by your shares rather than your personal assets. If your company doesn’t have a successful exit, you generally aren’t required to repay the financing from your own pocket. It’s also less likely to impact your debt-to-income ratio than a regular loan, which means it’s unlikely to interfere if you want to get a mortgage or loan from other lenders in the future.
Non-recourse financing means you can take part in potential upside if your company increases in valuation in the future, unlike if you sell shares immediately through a secondary sale.
We’ve provided over $800 billion in non-recourse financing to startup employees over the past decade, more than any other company that provides this service. If you have options with an eligible company, our equity strategists will walk you through a personalized proposal with potential outcomes and associated costs so you can make an informed decision.
An exercise decision rarely exists in isolation. Secfi’s Wealth Team can help you evaluate your equity alongside your taxes, cash flow, other investments, and longer-term financial goals.
That can be especially valuable if a blackout overlaps with a funding round, IPO, job change, or another major financial decision. Rather than looking only at whether you can exercise, an advisor can help you think through whether exercising makes sense for your individual situation and how much risk you’re comfortable taking. Our advisors have a fiduciary duty to act in your best interests, so they can’t (and won’t) pressure you into any decisions.
A stock blackout period can take certain decisions off the table temporarily, but you aren’t completely out of control. Understanding your equity, running the numbers under different scenarios, and thinking ahead about taxes and exercise costs can put you in a much better position when your window opens again.
Ask Maeve to explore how different valuations and exercise scenarios could affect your stock options, or talk to the Secfi team for personalized guidance if you’re facing a stock option blackout period or other equity decisions.
If your company’s blackout policy prohibits you from selling stock, you generally shouldn’t sell until the blackout ends. Doing so could violate your company’s insider trading policy and, if you’re trading while aware of material non-public information (MNPI), could also raise serious issues under federal securities regulation.
Public companies often impose blackout periods on certain employees and company insiders when they may have access to information that could affect the company’s share price but hasn’t been made public yet. The SEC prohibits insider trading based on material non-public information, regardless of whether a company blackout period is formally in place.
If you’re unsure whether a transaction is allowed, check your company’s insider trading policy and ask the legal or stock administration team before selling. If the blackout also affects a broader equity decision, Secfi’s Wealth Team can help you think through the financial implications once you know what transactions your company permits.
A trading blackout period is a period when a company temporarily prohibits certain employees, executives, directors, or other insiders from buying or selling company securities.
Public companies commonly have quarterly blackout periods around earnings releases, when employees may have access to financial results before they become public. Companies can also impose special blackouts around corporate events such as mergers, acquisitions, or other developments involving MNPI.
Trading blackouts are particularly relevant to employees whose equity compensation includes company shares, stock options, or other equity awards. The exact restrictions and dates depend on the company’s insider trading policy.
If you’re trying to understand how a blackout could affect the value, timing, or tax implications of your equity, Maeve can help you model different scenarios using your grant details.
No. A stock blackout period and an IPO lock-up period can both temporarily restrict stock transactions, but they happen for different reasons.
A stock blackout period is generally imposed by a company to restrict certain transactions for a limited period, such as while employees may possess material non-public information or while a major corporate event is underway.
An IPO lock-up period, by contrast, typically prevents employees, founders, and early investors from selling certain shares for an agreed period after an IPO. A company going public could therefore have a blackout period during the IPO process followed by a separate lock-up period after its shares begin trading.
If you’re approaching an IPO, Secfi can help you model how exercising before or after different company restrictions could affect your taxes, exercise costs, and potential future liquidity.
If you know a blackout period may be coming, first find out when it begins, which transactions it restricts, and whether you have any stock option exercise or expiration deadlines approaching.
For startup employees, it can also be useful to review your current 409A valuation, strike price, potential taxes, and exercise cost before the window closes. A funding round or other corporate event could change the company’s valuation while you’re waiting, so modeling different scenarios ahead of time can help you understand the possible impact.
Maeve can help you compare scenarios using different 409A valuations, exercise dates, and tax assumptions. If exercising before or after the blackout still makes sense, but the upfront cost is more than you want to put at risk personally, non-recourse financing from a provider such as Secfi may also be worth exploring.
If you work for a public company and regularly sell company shares, you may also hear about a Rule 10b5-1 plan. These plans can allow qualifying trades to occur according to instructions established in advance, subject to SEC requirements and company policies. They must generally be established when you aren’t aware of MNPI, and federal rules require a cooling-off period before trading begins under a newly adopted or modified plan.
Always check your company’s policies and speak with the appropriate legal, tax, or financial professional before making a transaction.
If your stock option exercise deadline falls during a blackout period, contact your company’s stock administration, HR, or legal team as soon as possible. Don’t assume the blackout automatically extends your deadline.
Some companies may provide additional time when an employee is unable to exercise, but the rules depend on your equity plan and company policy. If you’re leaving the company, this can be particularly important because your post-termination exercise window may continue running while the blackout is in effect.
For ISOs, there’s another tax consideration: under current U.S. tax rules, options generally need to be exercised within three months after employment ends to retain ISO tax treatment. Exercising later may cause the options to be treated as NSOs instead.
If the two deadlines overlap, get clarification from your company before assuming you can simply wait until the blackout ends. Once you know your available timeline, Maeve or Secfi’s Wealth Team can help you compare the financial impact of exercising at different points, and Secfi’s non-recourse financing may be an option if the main barrier is covering exercise costs and associated taxes.
The tool shown here uses artificial intelligence and is for illustrative purposes only and not necessarily indicative of future results and there is no guarantee that similar results can be achieved. The information provided by the tool is not professional advice and is not intended by Secfi, Inc., its affiliates, and Secfi representatives, to be deemed as investment, legal, tax or other professional advice or recommendations of any kind, or to form the basis of any decision to do or to refrain from doing anything. Secfi does not review the accuracy or completeness of the information provided to us within the tool.