Why the cost to exercise stock options gets more expensive over time
6 min
0 result
John’s a Director at Secfi, helping founders, executives and employees navigate equity compensation and access to liquidity through his expertise in finance.
On paper, the cost to exercise your stock options may seem pretty straightforward: take the number of options you want to exercise and multiply it by your strike price.
But, not so fast. Depending on how long you've waited to exercise and how much you've exercised across the years, the real cost could be far, far higher.
Anytime you exercise stock options, you may owe taxes. And things can get complex very quickly. Your tax bill is usually based on the difference between the amount you're paying per share (the strike price) and its fair market value at the time of exercise.
So if the company's value has markedly increased, so will the final cost to exercise your stock options. And if you're trying to figure this out alone, then you'll know that working out what the exact number will be is incredibly complex.
Luckily, this article was written to help you.
In it, we'll cover:
Note: Secfi helps employees understand, plan for, and finance major equity decisions, including when to exercise stock options. Model your specific situation with our free AI equity assistant Maeve.
The final cost of exercising your stock options comes down to several factors:
This number will differ for every situation, and working out the exact cost can be tricky. Here are the main two elements you need to be aware of:
The strike price, also known as the exercise price, is how much you'll pay to purchase one share in your company when you exercise a stock option. It's set when you receive your initial stock option grant, which will also spell out the number of options you're getting and their vesting schedule.
The strike price is typically set by the company's current 409A valuation, an appraisal of the current market price of a company's common shares for tax purposes. Every company that offers equity to its employees is required to get a 409A valuation, and re-valuations happen at least every 12 months, or whenever there is a material event (such as a new funding round) that may impact the company's valuation.
That means that the later you join a startup, the higher the strike price will be, assuming that the company has been increasing in value over time.
If you have multiple grants, each one will specify a different strike price. For example, if you receive more options as a bonus because your company is growing, then they'll likely have a higher strike price than your original grant.
Your strike price also never changes. It doesn't matter if you exercise right away, one year later, or ten years later. The strike price for all options from the same grant will remain the same.
If your strike price doesn't change, you might be wondering why the cost to exercise stock options can go up over time.
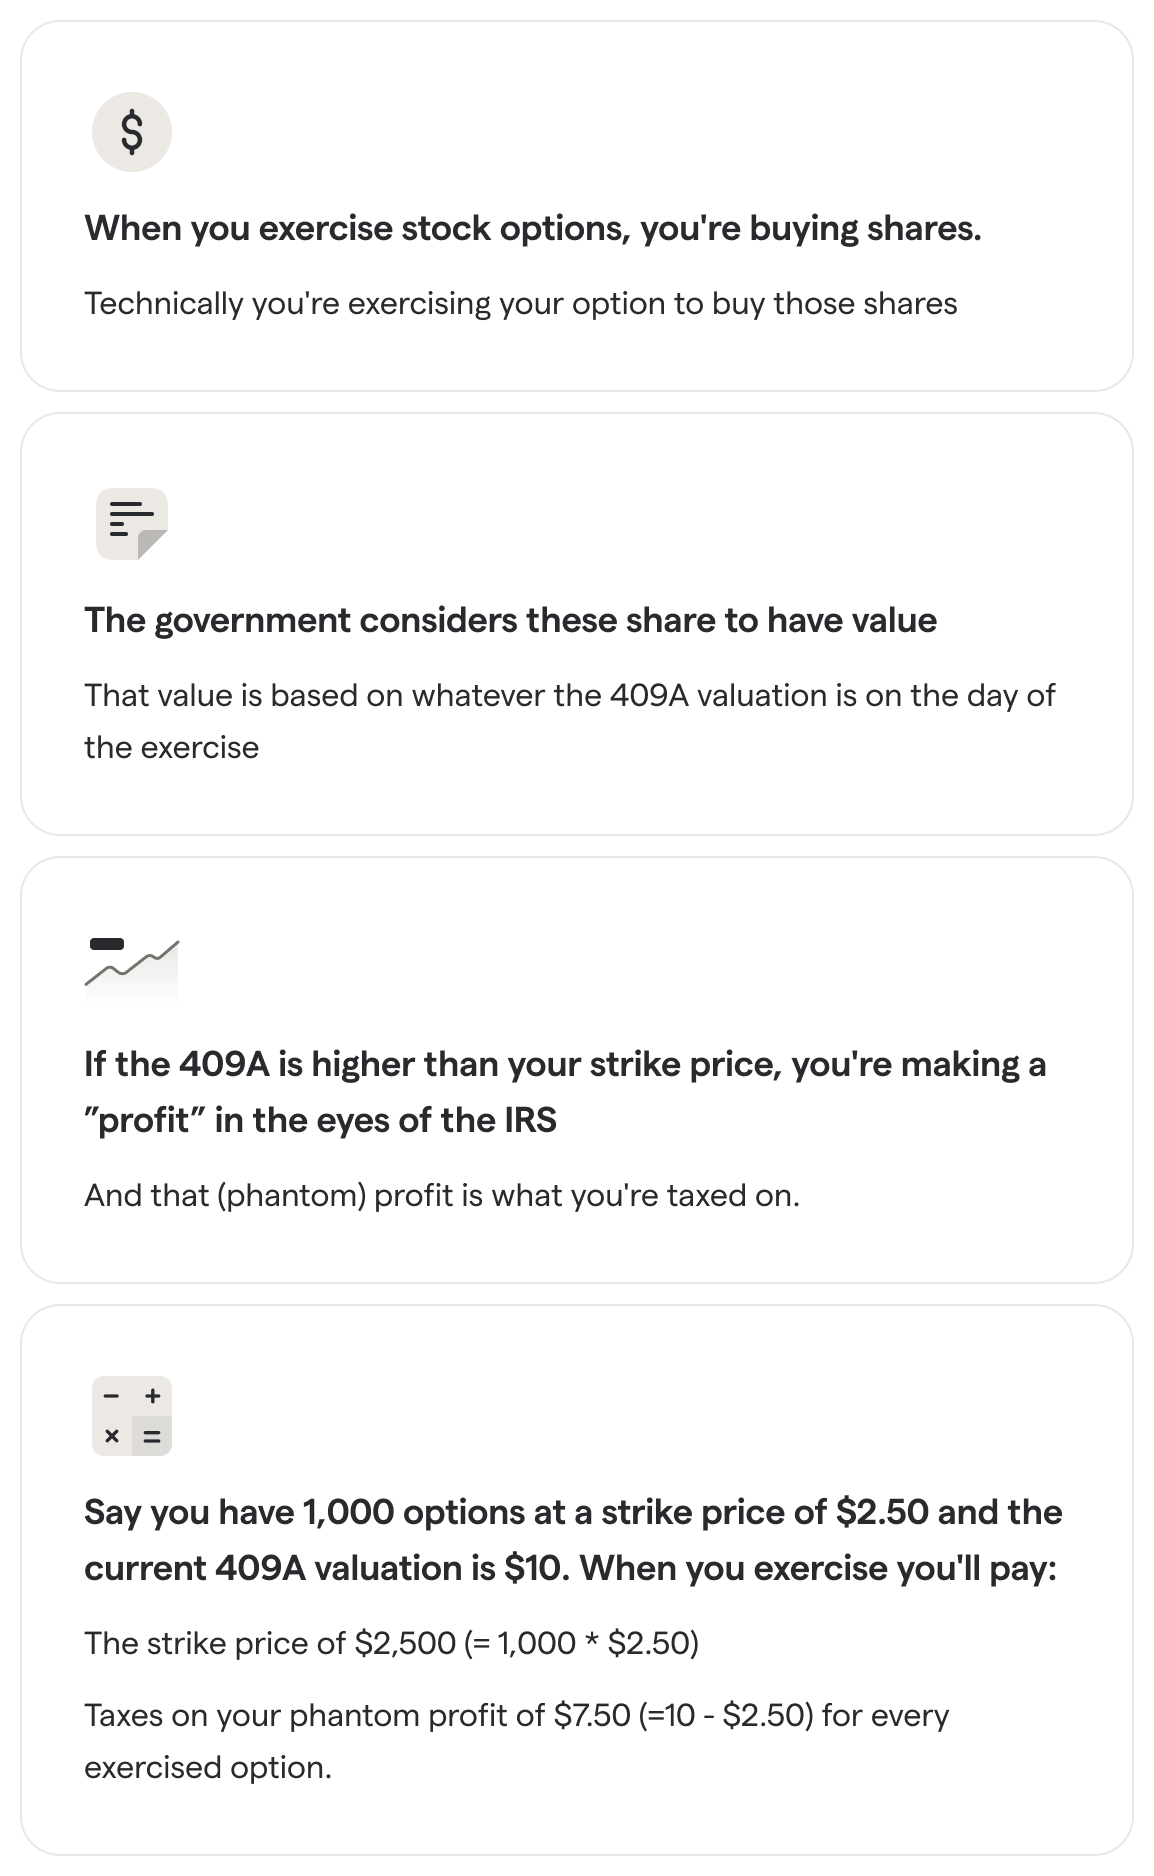
The answer is taxes. Stock options are taxed based on the difference between the strike price and the fair market value (FMV) (also called your 409a) of your shares. This is called the spread. If your company's valuation increases, so does the FMV, and so does your taxable spread. In other words, the larger the difference between strike and FMV, the larger your tax bill is going to be.
For NSOs (non-qualified stock options), the spread is taxed as ordinary income tax (up to 60% between Federal and State tax).
With ISOs (incentive stock options), there is more wiggle room to save on taxes, but the process is also a little more complicated. That's because whenever you exercise ISOs, you'll need to work out AMT on the spread. This is a separate tax system designed to make sure high-income earners pay an adequate amount of federal tax, and so it has different rules from the normal system.
The main things to know are:
You'll need to calculate both AMT and the amount due with the regular tax system, then compare the two tax bills, and pay whichever is higher. In general, AMT is triggered when the spread between strike price and FMV becomes large enough, so if you exercise only a small number of options at a time, you may be able to avoid paying it.
If not, AMT can get extremely expensive, extremely quickly.
This is the surprise factor, and where the real cost of exercising your stock options materializes. Looking at employees from companies like Palantir, Databricks, Snowflake, and DataRobot, the average surprise factor is 3.5x. It can also get as high as 9.5x.
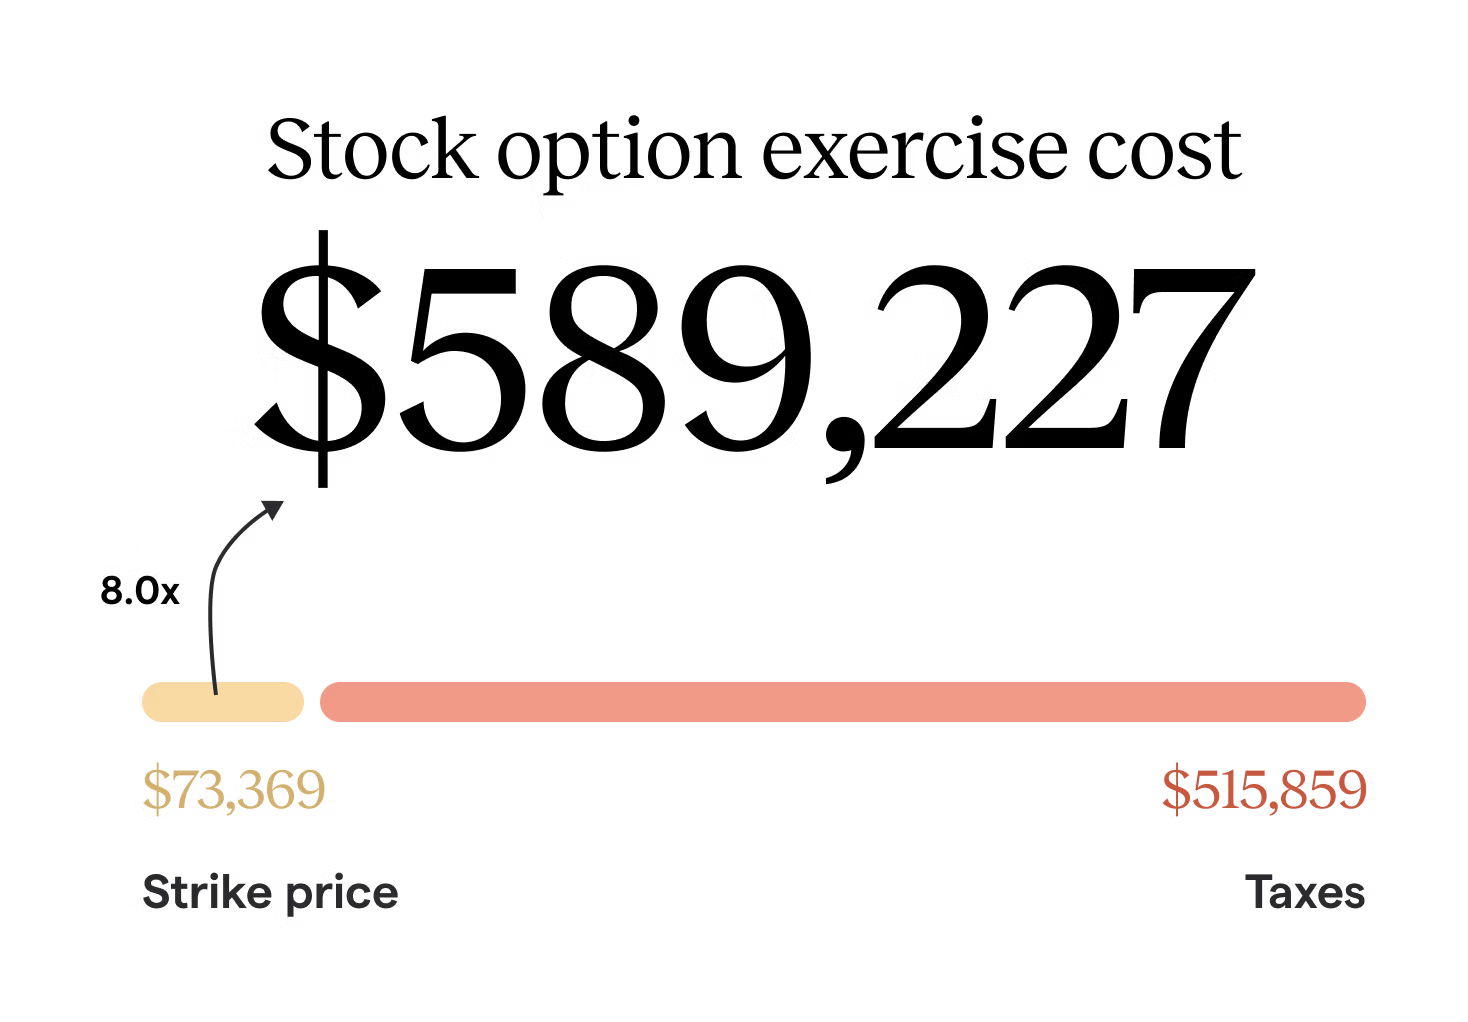
For illustrative purposes only. Actual results may vary and there is no guarantee of any particular outcome.
Definition: surprise factor = (exercise cost including taxes) / (strike price * number of options)
To exercise, you'll need enough cash to pay for not just the cost of the strike price, but the AMT bill as well.
For illustrative purposes only. Actual results may vary and there is no guarantee of any particular outcome.
There are several ways to reduce or avoid paying AMT altogether, but you have to be savvy to implement them.
It requires quite a lot of pre-planning and preparing to successfully optimize your ISO tax obligations, so using an AI assistant like Maeve can really help. Maeve is a free tool that can answer your questions on cost, taxes and when to exercise. It connects to your equity data directly and you'll get plain-English insights and explanations for your stock option planning. Try Maeve now.
Yes and no. If you trigger AMT, there is no way around paying it. However, if you plan ahead, there are ways to reduce your AMT or avoid triggering it altogether.
These are some things to consider:
None of these options are necessarily straightforward, which is why it's helpful to work with a wealth or financial advisor who can understand your specific situation.
It's also worth noting that you'll have to pay tax when you eventually sell your shares on the gains above your original strike price. If you exercise and hold them for at least 12 months before selling, you'll be taxed at the more preferable long-term capital gains tax rate. Depending on your income, this might be 0%, 15%, or 20%.
Selling sooner will mean the gains are treated as ordinary income, and taxed at up to 50%.
This is another way that waiting to exercise can leave you looking at an even higher tax bill.
This is a tricky question, especially as exercising your stock options can be the first major financial decision that you make. An equity investment will always come with some degree of risk, and in many cases, the earlier you invest, the riskier it can be. But the longer you wait, the higher the cost of exercising.
Balancing this risk/reward ratio is often one of the most important elements of deciding when to exercise your options.
These are the windows that exercising stock options can make the most sense:
Almost all stock option grants follow the same four-year vesting plan with a one-year cliff. So after one year, you'll get 25% of your options, with the remaining 75% vesting gradually over the next three years.
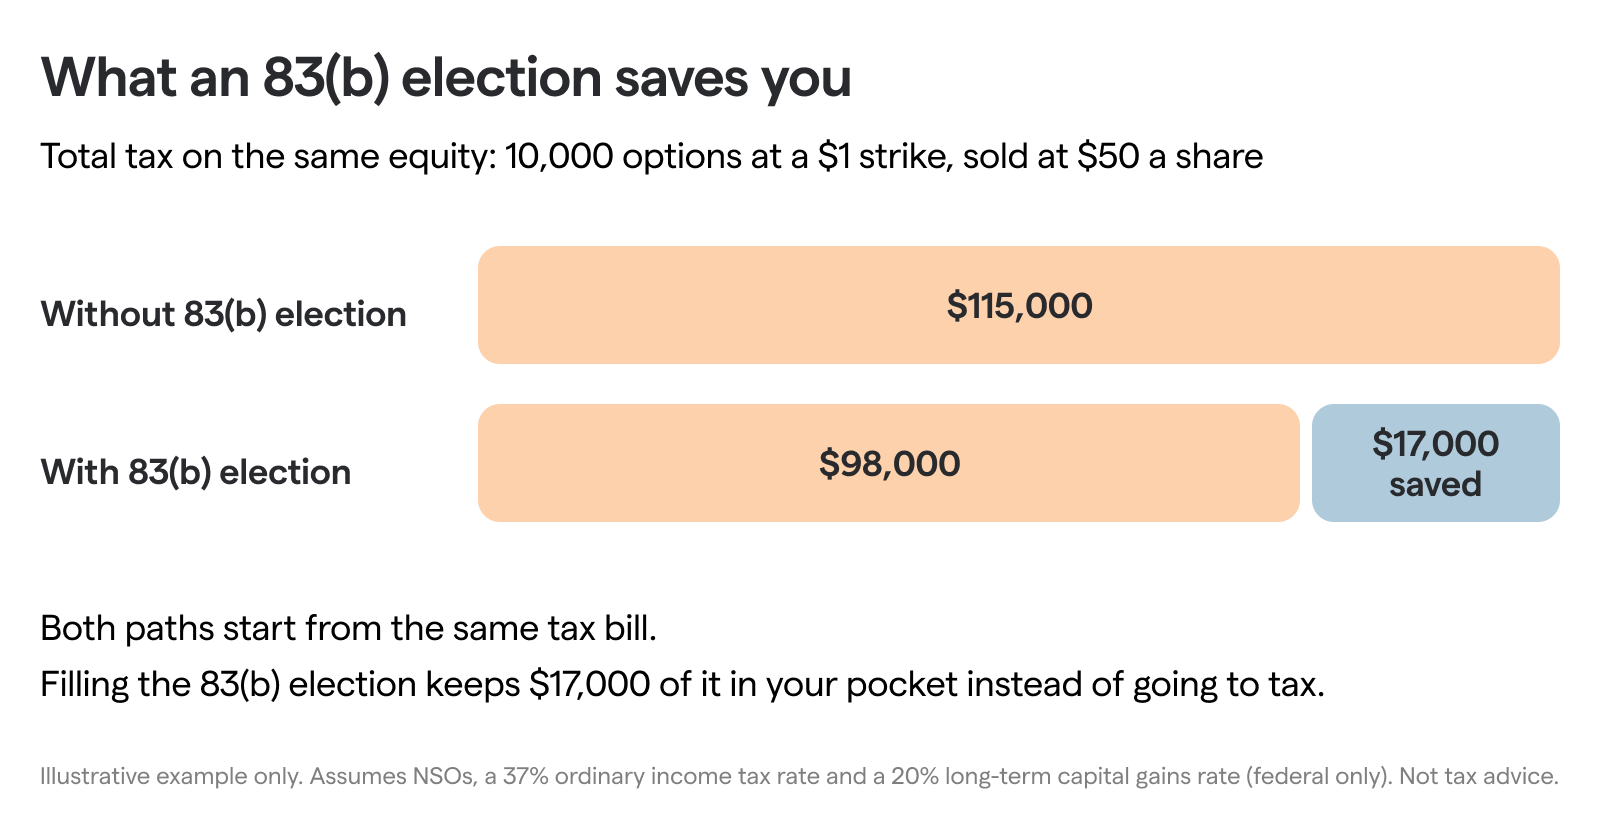
However, in some cases, companies will let employees do an "early exercise". This is when you can exercise your options before they vest and before you actually own them. If you then also elect to file an 83(b) form, you can elect to pay your taxes now, instead of when the options actually vest.
For illustrative purposes only. Actual results may vary and there is no guarantee of any particular outcome.
In other words, you can choose to pay your tax when the spread is at the smallest possible amount.
But there are some drawbacks:
A staged approach is where you exercise a portion of your options every year. This will mean multiple lower tax payments, instead of facing one giant bill. Or, if you're exercising ISOs and plan carefully to exercise a low enough amount, you might even avoid triggering AMT altogether.
This is because AMT is usually only triggered when the difference between your strike and the FMV becomes large enough. By keeping your yearly exercise numbers down, you could be able to stay below the AMT threshold.
For illustrative purposes only. Actual results may vary and there is no guarantee of any particular outcome.
Other factors do come into play that you might have to also balance out. For example, lowering your taxable income or maximizing your retirement contributions. Optimizing your AMT bill will heavily depend on your personal situation, so we always recommend speaking to a tax advisor beforehand. Tools like Maeve can also help you better understand your options.
A staged approach can be seen as a more balanced approach that makes managing the exercise price a lot more reasonable, while also starting the long-term capital gains clock early. Although there are still a few things to keep in mind:
Knowing that your company's 409A valuation is about to increase can be a great time to exercise. If you wait until after, you'll be paying a lot more in taxes, and the earlier you exercise, the earlier you start the long-term capital gains clock. That means the sooner you'll be able to sell at the lower taxation rate.
The biggest con of waiting for a liquidity event is that you can't always predict when one will happen.
In situations like a sudden acquisition, you might not know until it's happening. Companies are also under no legal obligation to tell employees if an IPO is on the horizon, although in a lot of cases you'll start to hear rumors at least a little way in advance.
It's also helpful to know about blackout periods, as companies often prevent employees from exercising options around the time of a fundraising round, including an IPO.
Another very common element of a stock option grant is the post-termination exercise window. It dictates that after leaving the company, you only have 90 days to exercise your vested options.
At this point, the question is no longer when to exercise, but whether you should at all. It puts a lot of pressure on the employee to both make the decision and find the cash to cover the cost.
You have to bear in mind that:
That's where Secfi's non-recourse financing can help. It's a cash advance that will cover the cost to exercise that you only have to pay back if the company has a successful exit. In other words, there are no upfront costs for you, and no risk if the equity ends up being worthless.
Not everyone will be approved for this type of financing. Get started to find out if you could be the right candidate for non-recourse financing.
Here's the good news: you don't have to face these complex decisions alone. Secfi was built by a team of tech employees who knew there had to be a better way to approach exercising, especially if you don't have the cash to exercise before the costs go sky high.
These are the tools and expertise that can help you:
To exercise your options you may be able to use your own cash, sometimes take out a loan, sell eligible shares, or wait for a cashless exercise.
Another option is to use non-recourse financing. This is a type of financing that gives you the money you need to cover the cost of exercising options and the associated taxes, without monthly repayments or putting your personal assets at risk.
It's a great alternative for anyone worried about the risk of exercising too soon. We'll assume all the risk associated with the exercise, and you do not have to pay anything back unless the company has a successful exit.
You can learn more about how this works in our guide to non-recourse financing.
Choose non-recourse financing if:
We've provided over $800 billion in non-recourse financing to startup employees and helped over 55,000 startup employees with their equity planning, working at companies like Databricks, Uber and Anthropic over the past decade.
If you have options with an eligible company, our equity strategists will walk you through a personalized proposal with potential outcomes and associated costs so you can make an informed decision.
There are so many factors to juggle when it comes to understanding the cost of exercising. AMT is extremely complex, and even though you know that planning early can reduce taxes, you still might not know where to start.
That's why we built Maeve, our AI equity assistant that unifies all your equity planning tools in one place, while also providing personalized answers to your questions.
It's free to sign up, and easy to get started. Just connect directly to your Carta account, upload your grant documents, or enter the details manually to get an instant look at your situation.
Maeve can tell you the exercise price and tax obligations of your stock options right now, as well as predict how that cost might change in the future. It will also provide helpful information on tax forms and deadlines that ensure you don't make an expensive mistake.
It's hard to find advisors who understand stock options, especially ones that are experienced with clients who are a little earlier in their wealth journey.
Deciding to exercise your employee stock options might be the first major financial decision you've faced. Pair that with more personal factors like a growing family, the want to buy a house, or other financial weights, and the pressure to make the right decision becomes even heavier.
But our team of financial planners is ready to step in and assist. Their advice is personal to you and your family because not everyone's financial goals are the same.
You will get support on:
A professional can best tailor your wealth management to not only have the best chance of success in the future, but to also fit with the life you're building now.
The general rule of thumb is: if your options are in the money and your company will continue to grow and have a great exit (IPO or get acquired), then exercising earlier is usually best. That's because you'll pay less to exercise and start the clock on long-term capital gains.
But other factors like cash flow issues and risk also have to be considered.
Secfi's equity strategy team specializes in solving these problems. They can help you optimize AMT, build an exercise plan, and navigate through an upcoming IPO in order to reach your personal financial goals.
While it is possible to sell an option on a secondary market, in most cases it is hard to actually execute. If a company is still private, finding buyers can be extremely difficult, and you may be limited by the terms of the grant as to how much and to whom you can sell your options. Selling also means you'll lose out on any potential upside in the future.
The main advantage of selling is to avoid the risk and cost of exercising. Something like a non-recourse financing loan is a great way to bypass both these concerns, while also keeping ownership of all of your equity.
There are several ways to exercise your stock options, but choosing the best will depend on your personal circumstances. Factors like risk tolerance, cash flow access, and how much you believe in the company all have to play a role.
Exercising earlier can reduce the spread between your strike price and FMV, but it also means putting your money at risk sooner. A good approach is to model several exercise dates and company-value scenarios using Maeve before deciding.
When it comes to funding the exercise, you could opt for a sell to cover transaction or a cashless exercise to avoid using your own capital. However, this will result in you paying the highest possible tax rate on any gains. If cash flow is an issue, non-recourse financing could be the best option.
Not necessarily. What happens to your stock options during an acquisition depends on the terms of the deal, tax implications, and your company's equity plan. Options may be cashed out, converted into the acquiring company's equity, or treated another way. However, an acquisition can affect both the value and tax treatment of your options, so it's worth understanding the deal terms and modeling the potential tax consequences before deciding whether to exercise.