Stock option valuation: How much are your startup options worth?
16 min
0 result
Mike’s a CPF® at Secfi. He specializes in helping clients make the most of their stock options and integrate equity compensation into their broader financial plans.
You get a startup job offer that includes stock options. Great, but how much are they actually worth?
For a private company, there usually isn’t one definitive answer. Stock option valuation means looking at several data points to estimate what your options might be worth today, and what they could potentially be worth in the future.
That uncertainty can make it difficult to compare your offer’s total compensation with another startup offer, or a public-company package where the value of the equity is easier to see.
And the question doesn’t disappear once you take the job. As your options vest and the company grows, you may need to decide how much weight to give that potential value when making bigger financial decisions, like:
If you exercise, will the tax bill take a serious bite out of your savings?
Can you sell some shares and finally put that money toward a house?
Is now a good time to exercise, or would waiting make more sense?
While the uncertainty isn’t always fun, you can use several data points to build a reasonable range for what your stock options may be worth today and at a future exit.
In this article, we’ll cover:
The main valuations you may see for your stock options
How to calculate a reasonable stock option valuation
How Secfi can help you understand and act on your stock option valuation
Why Victor went from modeling his stock options himself to making a plan with Secfi
Use Maeve, Secfi’s free AI equity assistant, or our MCP in Claude or ChatGPT to help figure out your stock option valuation.
When you’re trying to understand what your private-company stock options might be worth, you’ll probably come across different numbers that measure slightly different things.
| Valuation or price | What it means | What it can tell you | How often it can change |
|---|---|---|---|
409A valuation | An independent estimate of the fair market value (FMV) of your company’s common stock. | Helps you understand the current FMV of common stock and the spread between your strike price and FMV when exercising. | Generally refreshed at least every 12 months, or sooner after a material event such as a new funding round. |
Preferred share price | The price investors paid for preferred shares in a funding round. | Shows what investors paid at that point, although preferred shares may have rights common shares don’t. | Usually changes when the company raises a new priced funding round. |
Secondary market price | The price buyers and sellers are agreeing on for private shares. | Can provide a more current signal of what buyers may be willing to pay for shares. | Can move whenever new transactions or bids occur, sometimes much more frequently than a 409A. |
None of these figures give you a guaranteed value for your stock options. But looking at them together can give you a much better sense of the range you’re working with.
For example, your company could have a $20 409A value for common stock, a $35 preferred share price from its last funding round, and secondary buyers currently bidding closer to $28. None of those numbers is necessarily wrong.
This is a hypothetical example for illustrative purposes only. Your own outcome will depend on your situation, so check them with your tax or financial advisor.
The 409A valuation is intentionally conservative, calculated under strict IRS guidelines to minimize tax risk for the company. That's why it typically trails what investors are willing to pay. It also helps determine the strike price for new option grants. Companies generally set the strike price at or above the fair market value of common stock when the options are granted. Once set, your strike price stays fixed even if later 409A valuations change.
On the other end, the preferred price reflects what venture capitalists paid for shares with special rights, like priority payouts if the company sells, voting power, and protection against dilution.
Secondary buyers, who usually purchase common shares without those advantages, naturally want a discount. At the same time, they're paying a real market price rather than relying on a conservative fair market value (FMV) estimate, so their bids tend to exceed the 409A value.
The result is a range that captures both the floor (what tax authorities accept) and the ceiling (what institutional investors committed), with the secondary market finding a middle ground that balances risk and reward.
Despite all these variations, it’s possible to get a reasonable understanding of the value of your options. Knowing how to value your stock options can help you feel confident about negotiating a job offer or making decisions like when to exercise.
As a heads-up, we’re about to get into some example calculations based on our years of working with startup executives and employees at Secfi.
While it’s good to understand what goes into the valuation of your stock options, if you want to skip this and just get an estimate, try our free AI equity assistant Maeve. You can connect it to Carta in seconds, or manually upload relevant grant docs and data so you can get a quicker stock option valuation and start modeling different scenarios.
For illustrative purposes only. Actual results may vary and there is no guarantee of any particular outcome.
Your company should be able to provide you with the following figures:
The number of options you have under each grant and the strike price for each one. Your strike price was generally set using the FMV of your company’s common stock when your options were granted.
Your company’s fully diluted share count. This includes common and preferred shares, along with other securities that could potentially become shares, such as outstanding options.
Your company’s current 409A valuation/FMV. Compare this with your strike price to see the current spread on your options and estimate what exercising today could mean for their value and potential taxes.
If you don’t have the fully diluted share count, ask your company or check your equity documents first. You may be able to make a rough estimate using information from a recent funding round, but private-company capital structures can be complicated, so treat that number as an approximation.
Next, estimate what your company could be worth at a future liquidity event, such as an IPO, acquisition, or secondary sale. This gives you a starting point for modeling what your options could eventually be worth.
You can also run the calculation using a current company valuation, such as the valuation from its latest funding round, to get a rough present-day scenario. Just remember that this is usually based on preferred shares, so it may not reflect the value of your common shares today.
Let’s get into a hypothetical example, but remember to check with a qualified tax or financial professional for your own situation.
Say you have 1,000 options and your company has 100 million fully diluted shares:
1,000 ÷ 100 million = 0.001% ownership
If you then use a $1 billion company valuation as your scenario:
0.001% × $1 billion = $10,000 in gross potential value
That $10,000 doesn’t account for your exercise cost, taxes, or differences between the value of preferred and common shares. We’ll get to those costs in the next step.
You can then repeat the calculation using different future valuations. For example, what happens if the company’s value grows 2x or 5x? What if it stays roughly the same or declines?
Modeling several scenarios can give you a more realistic range than relying on a single projected exit valuation.
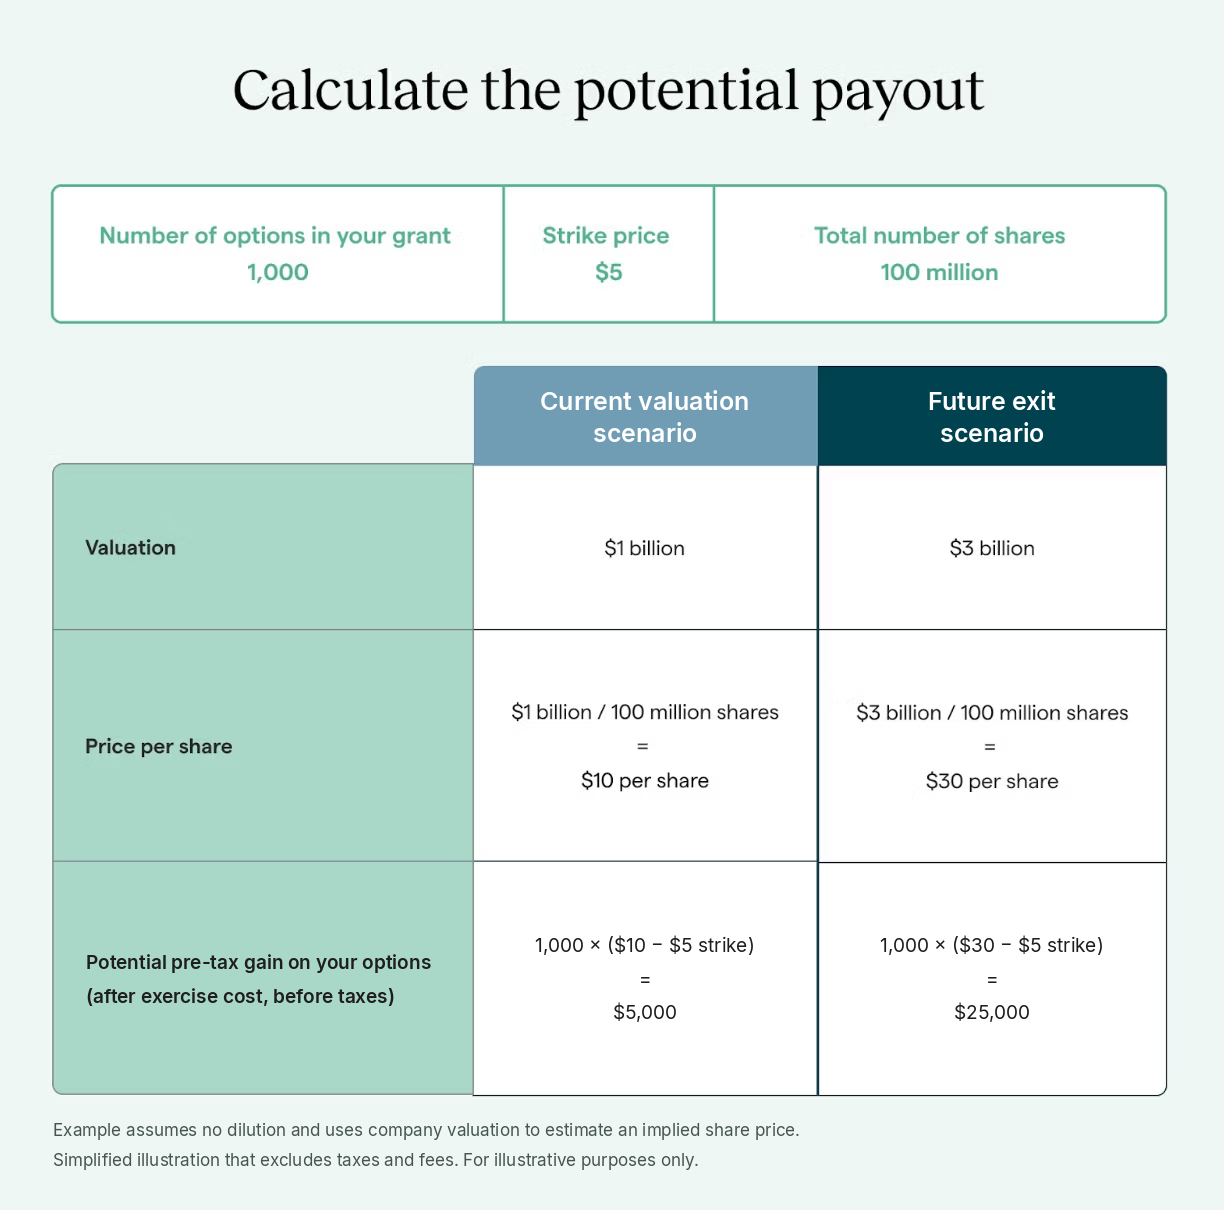
For illustrative purposes only. Actual results may vary, and there is no guarantee of any particular outcome.
It’s worth noting that our example is simplified and assumes no dilution takes place, which is not always a realistic assumption.
Dilution is when your company increases the number of outstanding shares. This happens during fundraising when your company issues new shares for investors to buy. Dilution means the exit value would be divided among more shareholders.
And of course, there’s no guarantee your company will have a successful exit. Private-company shares can lose value, and in some cases, they may ultimately be worth nothing.
To arrive at your potential take-home gains, you’ll need to subtract your costs from the resulting gain in the stock’s value. In some cases, the full cost to exercise for our clients has been more than 8 times what they expected, so this step needs to be done carefully with a professional.
Your costs have two parts:
1) The cost to purchase your options.
If you have multiple grants, you’ll need to calculate the cost for each one. Returning to the example in Step 2, say the company grows 3x to a $3 billion valuation. Your shares could have a gross value of $30,000, and with a $5 strike price, you’d pay $5,000 to exercise ($5 strike price x 1,000 options) to exercise your options. So, your projected gain before taxes would be $25,000.
2) Taxes (which depend on the type of stock options and when you exercise or sell).
Your tax treatment depends on whether you hold incentive stock options (ISOs) or non-qualified stock options (NSOs).
For ISOs, you generally don’t owe regular income tax at exercise, but the spread between your strike price and FMV can count as income for AMT purposes and may trigger the alternative minimum tax (AMT). When you eventually sell, additional taxes may apply depending on how long you held the shares and whether you met the ISO holding requirements.
For NSOs, the spread between your strike price and FMV at exercise is generally taxed as ordinary income.
With a cashless exercise, you exercise your options and immediately sell some or all of the resulting shares. Part of the sale proceeds covers your strike price and applicable taxes, so you don’t need to pay the exercise cost upfront. If you sell ISOs before meeting the required holding periods, some of the gain may be taxed as ordinary income rather than receiving qualifying ISO tax treatment.
Secfi started in 2017 because our founders knew first-hand how difficult (and expensive!) it can be to understand and act on their own stock options. As of July 2026, more than 62,000 startup employees and executives trust Secfi to help them make decisions about their stock options.
Here’s why employees and executives at companies like Anthropic, Stripe, and Klaviyo work with Secfi.
If the calculations earlier in this article made your eyes glaze over a little, you don’t have to build every scenario manually.
We combined years of our equity-specific calculators into Maeve, Secfi’s free AI equity assistant. You can use connected Carta data or grant information you upload manually to help organize your equity and model different scenarios.
For a stock option valuation, that could mean comparing your potential payout at several company valuations, estimating exercise costs and taxes, or seeing how exercising different numbers of options changes the outcome.
For example, you could ask:
“If my company exits at $5 billion, $10 billion, or $20 billion, what could my vested options be worth after estimated exercise costs and taxes?”
Maeve was developed because we found most LLMs made too many mistakes or lacked enough context to provide the type of tax and equity scenarios we’d want when planning our equity. While their answers sounded confident, text prediction didn’t allow for the same robust calculations we’ve used with our clients.
For illustrative purposes only. Actual results may vary and there is no guarantee of any particular outcome.
You can also connect your Maeve account to supported AI assistants in ChatGPT through Secfi’s MCP integration and ask questions using the equity data already in your account in your LLM of choice.
Sometimes even the best tools aren’t enough when we’re making decisions that impact our financial lives.
Secfi’s financial advisors specialize in private-company equity and can help you work through questions such as which valuation data is most relevant and how different scenarios could affect your potential outcome. They have a fiduciary duty to act in your best interests and work on a fee-only basis, so they don’t push products to get a commission.
Our advisors can be especially useful when you have multiple grants, a large amount of your net worth tied up in one private company, or several plausible valuation scenarios and aren’t sure how to compare them.
Sometimes the calculation shows that your options could have potentially life-changing value, but exercising them would need more cash than you’re comfortable putting into an illiquid private company.
For eligible employees, Secfi offers non-recourse financing that may cover the cost of exercising stock options and associated taxes. Repayment is tied to the terms of the financing agreement and a future liquidity event, so you don’t need to make monthly payments.
Because the financing is non-recourse, if the shares don’t produce enough value under the terms of the agreement, Secfi bears the downside rather than pursuing your other personal assets like your house or savings.
You still own the shares and can participate in potential upside, don’t need to fund the entire cost to exercise with your savings, and your other assets are safe if your company doesn’t have a successful exit. So, what’s the catch?
Non-recourse financing is selective and isn’t available for every employee or company. Eligibility depends on factors such as the company, your equity, the expected path to liquidity, and the specific financing terms. Financing may also require company approval depending on the transaction and your company’s policies.
We also offer support with secondary sales for your shares, which also depends heavily on your company’s valuation and willingness to let you participate.
Victor, an engineering leader at a successful pre-IPO company, was already financially savvy. But when it came to his ISOs, he found himself building a chart to model different scenarios and trying to answer questions around exercise timing, taxes, AMT, and risk.
When he calculated the potential AMT bill to exercise, the total cost felt “possible, but not comfortable.” After working through his options with Secfi, Victor decided to use non-recourse financing to cover his exercise costs and potential AMT bill without putting his other personal assets on the line.
“It’s amazing that companies that give a huge amount of value to their employees in the form of stock options quite often don’t do a good job of explaining how it all works,” he said. “Usually it’s like, ‘Hey, here’s a pool with sharks. Go swim, enjoy.’”
Victor said he chose Secfi because the team was responsive and walked him through how exercising his stock options could trigger AMT and what that might mean for his long-term taxes, all in plain language so he could make a decision that fit his personal finances.
“Secfi was definitely the best,” Victor said. “I got responses immediately, it was amazing.”
Read the full case study: Why this engineering leader chose Secfi to finance his stock options.
This case study is an illustration of our capabilities provided to an individual client. Client results may vary, and there can be no guarantee of similar results. It is not known whether the client approves or disapproves of Secfi Advisory Limited or its affiliates as a whole. Unless otherwise indicated, Clients offering a Testimonial do not receive compensation and their statement does not present a conflict of interest.
Your stock option valuation is ultimately an estimate. But with the right inputs, you can model a realistic range, account for exercise costs and taxes, and make a more informed decision about what to do next.
Our free tools like Maeve and the Secfi MCP can help if you want a quick estimate, or you can connect directly with our team for a free consultation if you’re interested in financial planning or non-recourse financing.
For employee stock options, a simple starting point is the option’s intrinsic value: subtract the exercise price (or strike price) from the current value of one share, then multiply that spread by the number of options you can exercise. If the share value is above your exercise price, the option is in-the-money.
That doesn’t capture the option’s time value or factors such as expected future volatility, though. For your own equity compensation, Secfi’s Maeve can help model different company valuations, exercise costs, taxes, and exit scenarios using your grant details. You can also connect your Secfi data through Secfi’s MCP integration or work through the calculations with a financial advisor who specializes in private-company equity.
The $100,000 rule applies to incentive stock options (ISOs). Under IRS rules, no more than $100,000 worth of shares can first become exercisable as ISOs in a calendar year, based on the shares’ fair market value at the grant date. Any amount above that limit is generally treated as non-qualified stock options (NSOs).
That means your vesting schedule can affect whether the rule comes into play. It’s also separate from an early exercise, which specifically means exercising options before they vest when your plan allows it.
For a standard call option, models such as Black-Scholes commonly look at five core variables: the current share price, the exercise price, the option’s remaining or expected term, expected volatility, and the risk-free interest rate. Dividend yield may also be included where relevant.
This type of option-pricing model is different from simply estimating what your startup options could pay out. Companies may use valuation models to determine the grant-date fair value of employee stock options for stock-based compensation reported in their financial statements. Employees are usually more interested in questions like what their shares could eventually be worth, how much exercising could cost, and what taxes might reduce the final payout. Secfi Wealth’s financial advisors can help you answer these questions for your equity.
Private-company stock options are harder to value because there’s no public share price you can check. Your company’s 409A valuation provides a fair market value for common stock, while its latest preferred share price, secondary-market activity, and possible future exit values can provide other useful reference points.
Your exercise price is fixed when your option is granted, so comparing it with the company’s current fair market value can show whether your options are currently in-the-money and how large the spread is. Secfi can add more context through private-market insights, Maeve scenario modeling, its MCP connection, and financial advisors who specialize in private-company equity. If you decide exercising makes sense, but the upfront cost is too high, eligible employees may also be able to explore Secfi’s non-recourse financing.
The tool shown here uses artificial intelligence and is for illustrative purposes only and not necessarily indicative of future results and there is no guarantee that similar results can be achieved. The information provided by the tool is not professional advice and is not intended by Secfi, Inc., its affiliates, and Secfi representatives, to be deemed as investment, legal, tax or other professional advice or recommendations of any kind, or to form the basis of any decision to do or to refrain from doing anything. Secfi does not review the accuracy or completeness of the information provided to us within the tool.